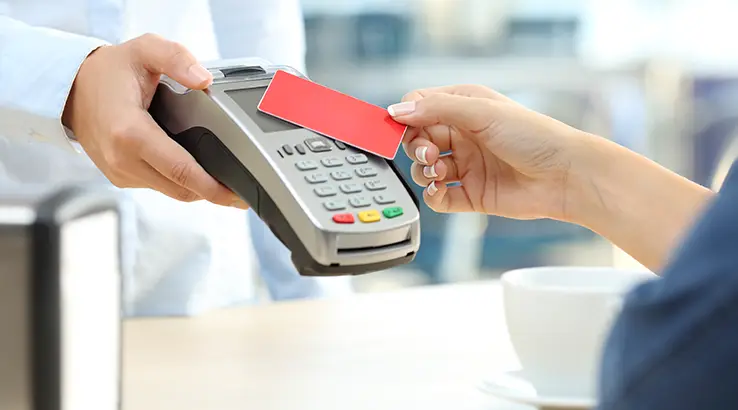
Contactless payments are a modern way to pay for your everyday purchases with one simple touch. To enjoy this benefit, you need to wave or tap your card, wearable payment device or smartphone in front of a contactless terminal. There’s no requirement to enter your PIN or sign a receipt to authorise a transaction.
This method has been used in the UK since 2007, with transaction limits gradually increasing. In March 2026, the manadatory £100 spending limit was removed by the Financial Conduct Authority, allowing banks and customers to set and customise their own limits, though banks like Santander and HSBC have kept the £100 limit due to risks of card fraud.
Still, the popularity of contactless payment increases, shifting the UK towards a cashless society, as the UK Finance estimated that a third of all payments made in the UK in 2021 used contactless.
How do contactless payments work?
Contactless payments use Near Field Communication (NFC), which allows two devices to securely transmit and receive information by bringing them within 4cm of each other. It’s an upgrade to the existing radio-frequency identification (RFID) technology, which combines the interface of a smartcard and a reader into a single device. As an example, RFID is used by Transport for London’s Oyster Card ticketing system.
If you see the contactless symbol, it means you can make contactless payments of up to limit set by you or by your bank. All three networks – Mastercard, Visa and American Express – offer contactless payment technology. Sometimes referred to as “tap and pay”, consumers can either wave or tap their credit cards at counters or card machines with contactless terminals without entering a PIN or signing a receipt. For larger transactions of over £100, you are usually required to enter your PIN. After you have tapped or waved, wait a few seconds for a green light or “approved” to show up to confirm that the transaction has gone through. You won’t always get a receipt so be sure to ask for one if you require a record of your transaction.
Contactless devices include:
- Debit, credit or pre-paid cards
- Mobile devices, such as smartphones and tablets (which use mobile payment systems such as Apple Pay, Google Pay or Samsung Pay)
- Wearable devices, such as watches and wristbands
- Key fobs
- Stickers
It’s worth noting that mobile payment devices usually don’t have a payment limit because they require an extra level of identification, such as a PIN, face scan or fingerprint.
What are the pros and cons of contactless payments?
Pros
- Convenient. You just need to tap your card or mobile phone and you don't need to enter a PIN or sign a receipt. This saves you time and doesn't cost you any extra money.
- Peace of mind. You're protected against fraudulent transactions, and retailers no longer have access to your credit card information.
- Reduces the threat of hackers. NFC technology uses data encryption when sending sensitive information, generating a one-time secruity code instead of your actual card number that hackers cannot use when making a second transaction.
- No typing errors. You don't have to worry about incorrectly typing in your PIN, and the connection is quicker on contactless terminals.
- Easy to use overseas. You can use contactless payments abroad if the retailer offers it, although the spending limit may vary depending on the local currency. Be aware: foreign transaction fees could still apply.
- Shorter queues. Convenient and quick payments mean fewer queues at the checkout.
Cons
- Some risk. If you lose your credit card, your account may be compromised.
- Easy to lose track of spending. It's easy to spend money when all you have to do is tap, and you don't always receive a receipt. Make sure to regularly check your bank statement for potential errors or fraudulent transactions.
- Risk of spyware or malware attacks and other viruses. Like any computer device, the payments terminal is at risk of viruses.
- The limit is set. Some banks set the maximum spending limit, though some do allow you to set your own limits.
- Confusing bank statements. Some retailers may use a different trading name so transactions could look confusing when they come up on your bank statement.
- Consider your credit rating. If you've got a poor credit rating, your provider may not offer you a contactless card.

Compare cards by type
We currently don't have that product, but here are others to consider:
How we picked theseFinder Score for credit cards
To make comparing even easier we came up with the Finder Score. Costs, perks and suitability across 120+ cards are all weighted and scaled to produce a score out of 10. The higher the score the better the card – simple.
Read the full methodologyWe currently don't have that product, but here are others to consider:
How we picked theseFinder Score for credit cards
To make comparing even easier we came up with the Finder Score. Costs, perks and suitability across 120+ cards are all weighted and scaled to produce a score out of 10. The higher the score the better the card – simple.
Read the full methodologyWe currently don't have that product, but here are others to consider:
How we picked theseFinder Score for credit cards
To make comparing even easier we came up with the Finder Score. Costs, perks and suitability across 120+ cards are all weighted and scaled to produce a score out of 10. The higher the score the better the card – simple.
Read the full methodologyWe currently don't have that product, but here are others to consider:
How we picked theseFinder Score for credit cards
To make comparing even easier we came up with the Finder Score. Costs, perks and suitability across 120+ cards are all weighted and scaled to produce a score out of 10. The higher the score the better the card – simple.
Read the full methodologyWe currently don't have that product, but here are others to consider:
How we picked theseFinder Score for credit cards
To make comparing even easier we came up with the Finder Score. Costs, perks and suitability across 120+ cards are all weighted and scaled to produce a score out of 10. The higher the score the better the card – simple.
Read the full methodologyApple Pay
Using a credit card with Apple Pay

- Which devices are compatible with Apple Pay? Apple Pay is only available on Apple devices. It is supported on newer model iPhones, iPads, Apple Watches and Macs. If you’re on an older iPhone device that runs an older iOS variant, you’ll have to update if you want to access Apple Pay.
- Which banks support Apple Pay? A wide variety of UK banks support Apple Pay, including Barclays, Halifax, HSBC, Lloyds, Nationwide and NatWest. If your preferred bank hasn’t launched Apple Pay yet, it might be wiser to wait for it to adopt the technology rather than to apply for the card now.
- What features do I need to consider? Just like any other type of credit card, you’ll want to consider the rates, fees and perks of the different types of cards that boast Apple Pay.
Google Pay
Using a credit card with Google Pay

- Which devices are compatible with Google Pay? Almost all Android smartphones with NFC (Near Field Communication) can take advantage of Google Pay.
- Which banks support Google Pay? Google Pay is supported by Mastercard and Visa credit cards from a wide range of UK banks including Halifax, HSBC, Nationwide, Lloyds Bank, MBMA and M&S Bank.
- What features do I need to consider? Just like any other type of credit card, you’ll want to consider the rates, fees and perks of the different types of cards that boast Google Pay.
Frequently asked questions
More guides on Finder
-
Credit card reward – terms & conditions
Finder credit card reward – Terms and conditions
-
Dragon Pass review 2026
Find out how you can book access to airport lounges across the globe with Dragon Pass.
-
NewDay, new review: Is Pulse’s exclusive card any good?
Find out how the new Pulse credit card works and who is eligible.
-
Overdraft or credit card: Which is better to borrow money?
Discover more about how credit cards and overdrafts work to see which option is best for you.
-
Credit cards for good credit 2026
Discover the best credit cards available for those with good credit.
-
Top ethical credit cards
Learn more about how ethical credit cards work and whether they are right for you.
-
Credit cards for the self-employed
It can be harder to get a credit card when you’re self-employed. But not always. Here’s how to boost your chances of being approved.
-
When is the Apple Card credit card coming to the UK?
Apple has announced its first credit card, the Apple Card, to be used with Apple Pay. Here’s how it works and what we can expect from it once released.
-
Compare The Co-operative Bank credit cards
Looking for a 0% balance transfer, 0% purchase or rewards card? The Co-operative Bank has a card for most typical situations. Learn more about the range and compare rates, fees, limits and eligibility requirements.