Best credit cards to use abroad in 2026
Pick a card with no foreign transaction fees and save big. We've rated 20+ cards for spending abroad and listed the best 3. Updated daily.
We currently don't have that product, but here are others to consider:
How we picked theseTo make comparing even easier we came up with the Finder Score. Costs, perks and suitability across 120+ cards are all weighted and scaled to produce a score out of 10. The higher the score the better the card – simple.
Read the full methodologyChoosing the wrong credit card can be incredibly costly if you get caught by expensive foreign transaction fees when you’re off catching some winter sun or shopping for some last minute gifts from an overseas business. The credit cards featured on this page are specifically designed to avoid costly conversion fees.
A travel credit card is simply a credit card that’s specifically designed for overseas use. Unlike standard credit cards, a travel credit card can help you avoid paying hefty foreign transaction fees when you spend or withdraw cash on your credit card abroad.
It’s important not to confuse travel credit cards with airline credit cards which offer rewards such as air miles.
A travel credit card works in much the same way as any other credit card. You can spend on your credit card as and when you need to, up to your set credit limit, and then you repay the amount borrowed in flexible monthly repayments. If you don’t pay off the balance in full each month, interest is usually charged.
Where they differ is that travel credit cards won’t charge a foreign transaction fee when you spend on the card overseas. Some also won’t charge a fee when you withdraw cash from an ATM. However, in most cases, interest is still charged on cash withdrawals from the moment you get your cash – even if you pay off your balance in full that month.
There are different fees you could end up paying on your credit card when you travel overseas. These include the following:
(charged by your card issuer)
Most credit cards in the UK market charge you a fee for every non-sterling transaction. Usually this is between 2% and 3% of the amount spent. For example, if your card had a fee of 3%, and you made a purchase for £100, this would cost you £3 in fees.
Best way to avoid this fee: Opt for a credit card that doesn’t charge foreign currency conversion fees.
(charged by your card issuer)
Withdrawing cash on a credit card at home or abroad is usually a bad idea because you’ll be charged a fee of around 3%. Even cards that bill themselves as specifically designed for travel may still charge this. When abroad, you’ll be charged this fee on top of any foreign transaction fee, which means if you withdraw £100, you could be charged a 3% fee for the cash withdrawal (£3) and a 3% foreign transaction fee (£3), bringing your total charges to £6.
Note that cash advances are also usually exempt from any interest-free days, which means you’ll be charged interest from the date of the transaction – even if you pay off your balance in full that month. Interest rates are usually higher too.
Best way to avoid this fee: Don’t withdraw cash using a credit card.
(charged by the cash machine provider)
Some ATMs will also charge you a fee of around £3 for withdrawing cash so make sure you check first.
Best way to avoid this fee: Don’t withdraw cash using a credit card (and for debit/prepaid cards, look for an ATM that won’t charge you for withdrawing cash.
(charged by the merchant’s bank)
Ever been asked by a merchant if you’d like to pay for your goods in sterling rather than the local currency? If you have and you accept, the retailer will do the currency conversion for you but likely at a less competitive exchange rate. This means you’ll pay more than necessary for your purchase. Similarly, at a cash machine, if the bank the machine’s attached to converts the currency for you, it’ll be their fee structure which will apply.
Best way to avoid this fee: Get a card with no overseas fees and then always pay in the local currency.
And a final extra “pro tip”: if you’re an Uber user and you get yourself a dedicated card with no fees on overseas spending, set it up as your default payment option before you go (because you’ll get billed in the local currency).
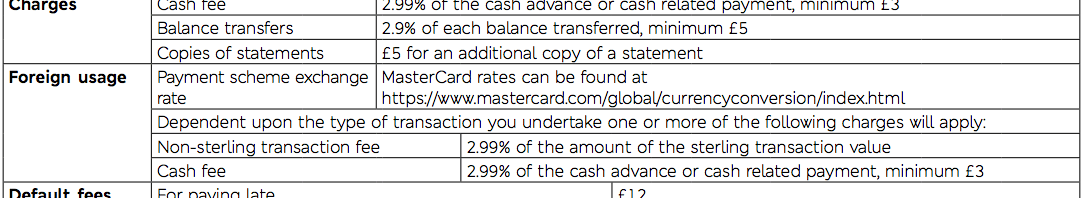
Here’s a section from a popular credit card’s summary box which serves as an example of how much extra you could pay to use your credit card abroad.
Underlying each credit card’s exchange rate is the network’s exchange rate. When you use a Visa card to pay for something in a different currency, Visa’s exchange rate is used. When you use a Mastercard, it’s Mastercard’s exchange rate that applies. Card issuers then normally add their own charge on top of this, but if you’re using a card that doesn’t charge non-sterling transaction fees (like those listed on this page), you’ll enjoy the network’s exchange rates with nothing added on top.
Alternatively, if you’re on Team Amex, here’s our guide to using your American Express card abroad.
If you’re looking for a credit card to take with you on holiday, you’ll need to consider the following when carrying out your comparison:
Credit card promotions have to include an annual percentage rate (APR) which all card issuers must calculate in the same way.
Credit card fee structures can get fiddly, so the APR’s designed to benchmark the yearly cost to borrow, with a view to helping consumers compare cards against one another. It takes into consideration the default interest rate plus any mandatory, regular account fees.
However, be aware that APR doesn’t take into account other fees such as those you may be charged when you travel abroad. A credit card that doesn’t charge foreign transaction fees might have a higher APR than other types of credit cards, but it will save you a lot in fees if you regularly travel abroad. Provided you clear your balance each month, the fact it doesn’t charge fees will be of more importance than the APR.
Finally, always keep in mind that credit card companies only have to offer their advertised representative APR to 51% of the people who are approved for the card. The rest may get a higher rate depending on their circumstances. That’s why it’s usually referred to as “representative” APR.
Travel credit cards aren’t for everyone and you typically need to have a pretty healthy credit rating to receive the most competitive rates. With a travel debit card, fee-free overseas spending is still possible, and you won’t have to worry about going into debt (unless you go into an unplanned overdraft).
You can use our guide to compare a range of low or no-fee debit cards.
Before you apply for a travel credit card, there are a few key points to be aware of.
For a start, while using a credit card can enable you to side-step sneaky foreign transaction fees, it can also encourage you to spend money you don’t have. If you don’t pay off your balance in full each month (or you withdraw cash on your card), the amount of interest you’ll pay can far outweigh any benefits of using the card itself. For this reason, it’s important to stick to a budget, make sure you don’t overspend and always do your best to clear your balance each month.
If you’re worried about this, you might prefer to use a prepaid currency card or a debit card instead. Some of these cards can also help you to avoid paying foreign transaction fees, but make sure you check first. Prepaid cards can be loaded up with currency before you go on holiday and you can then only spend what’s on the card, making them a good option for budgeting. A debit card lets you spend the money you have in your current account.
Technically, you can add funds to your credit card account before you go on holiday too, and then spend these funds in the same way as a debit card. This can help you to avoid paying interest.
However, card providers don’t take any responsibility for funds you add to your credit card account. So, if your card is lost or stolen and used for unauthorised transactions, you might lose out on valuable funds.
Finally, be aware that while a travel credit card can offer you a good deal while you’re abroad, it might not offer the best solution when you’re back home. For this reason, you might want to keep your travel credit card for overseas spending only, and use a different type of credit card when you’re home.
Compare more travel money options
If you’re a frequent traveller or regularly shop online with international retailers, using a credit card that doesn’t charge foreign transaction fees can save you a lot of money.
When deciding which card is right for you, check exactly what fees you could be charged and whether you will benefit from any perks such as cashback on purchases or reward points.
Keep in mind that even if your card doesn’t charge a fee for cash withdrawals, this type of credit card transaction is usually best avoided as you are likely to be charged interest from the date of the withdrawal.
Once you’ve done your homework, the next step is to use an
to find out which cards you’ll get approved for. If you haven’t done so already, it’s worth checking your credit score and report first so that you know how likely you are to get accepted. The better your credit score, the higher your chances of acceptance.
Finder credit card reward – Terms and conditions
Find out how you can book access to airport lounges across the globe with Dragon Pass.
Find out how the new Pulse credit card works and who is eligible.
Discover more about how credit cards and overdrafts work to see which option is best for you.
Discover the best credit cards available for those with good credit.
Learn more about how ethical credit cards work and whether they are right for you.
It can be harder to get a credit card when you’re self-employed. But not always. Here’s how to boost your chances of being approved.
Apple has announced its first credit card, the Apple Card, to be used with Apple Pay. Here’s how it works and what we can expect from it once released.
What are contactless payments? How do they work? Are they safe? Here’s what you need to know about tap and pay.
Looking for a 0% balance transfer, 0% purchase or rewards card? The Co-operative Bank has a card for most typical situations. Learn more about the range and compare rates, fees, limits and eligibility requirements.