Monese is a digital banking app and card using smartphone technology to improve your banking experience. Monese is great for travellers and works well if you are looking to set up an account quickly in another country. Let’s take a closer look.
How we scored Monese
| Feature | Rating | Details |
|---|---|---|
| App rating | 9 Excellent | Monese scores highly across the App Store and Google Play. |
| Monthly fees | 10 Excellent | Monese is free to use, with no monthly fee. |
| Transaction fees | 8 Great | Pay a fee to deposit cash, withdraw funds at an ATM, and receive your card. |
| Overseas fees | 6 Standard | A fee applies to both purchases and cash withdrawals abroad. |
| Customer service | 5 Standard | Monese scored just above average for customer satisfaction. |
| Green credentials | 7.5 Great | Monese was not included in the Finder Green Banking Awards. |
| Account access | 6.3 Standard | Account access is limited to mobile and online banking. |
| Payment features | 8.3 Great | Most payment features are available, but Monese doesn’t offer cheque deposits or a cashback or rewards programme. |
| Extra features | 9 Excellent | Benefit from spending categories, budgeting tools, savings pots, and more. |
What is Monese?
Monese has provided basic banking on smartphones since 2015. It gives people in the UK and abroad a chance to experience streamlined, modern finance.
This feature is what makes Monese unique: the ability for anyone to open an account anywhere in the UK or continental Europe. Whether or not you have a UK address, a credit history or fixed income, you can access Monese and open an account today. The app is currently available to anyone in the European Economic Area.
Monese is completely portable across 31 countries across Europe and, if you move to another country, your Monese account goes with you.
How does Monese work?
Monese works like a traditional banking system, but more streamlined. Like with most digital-only accounts, it’s all managed through the app. You can choose from a free account or pay for the Everyday, Cashback or Premium plans.
Below are some of the key features and benefits of Monese:
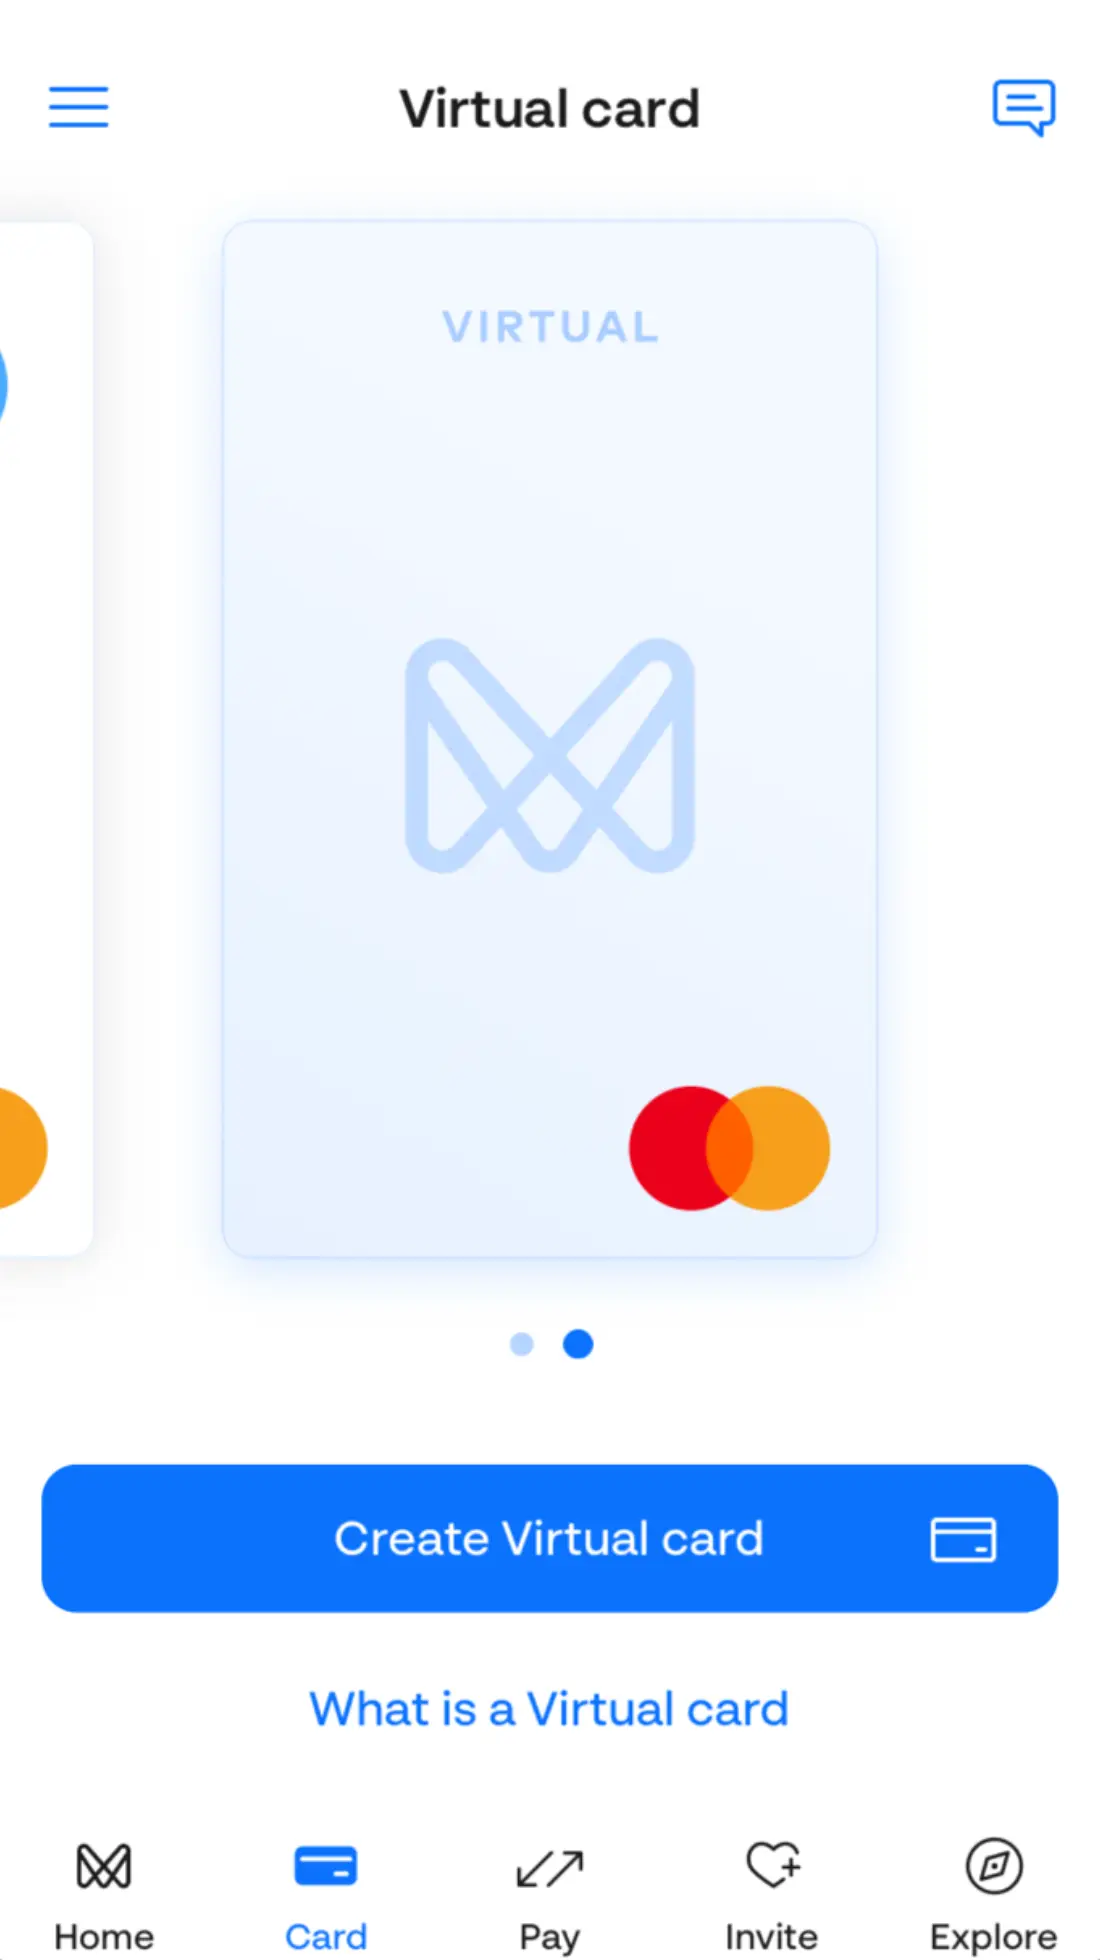
- Debit card. Order and manage your contactless debit card. You can see whether your card is active and get a reminder of your pin.
- Support. The support tab in the app provides customers with easy access to customer service via telephone, instant messenger or email. This tab also has an FAQ section.
- Direct debits. View and manage your active direct debits. Your account number and sort code are provided on this page for you to copy.
- Add Eurozone account. Add a Eurozone account at the click of a button. You can switch between your UK and European accounts at any time on the home page.
- Earn cash when referring friends. Invite a friend to join Monese and you can earn money.
- Interest-free credit builder. For a monthly fee, you can build your credit history and savings through the Credit Builder feature. As you make your monthly repayments, these are reported back to the credit reference agencies.
- Link your bank account. Through Open Banking you can easily link a UK bank account and manage all your money accounts and balances from the app.
- Budgeting tools. You’ll easily be able to keep track of your spending and even set yourself budgeting goals.
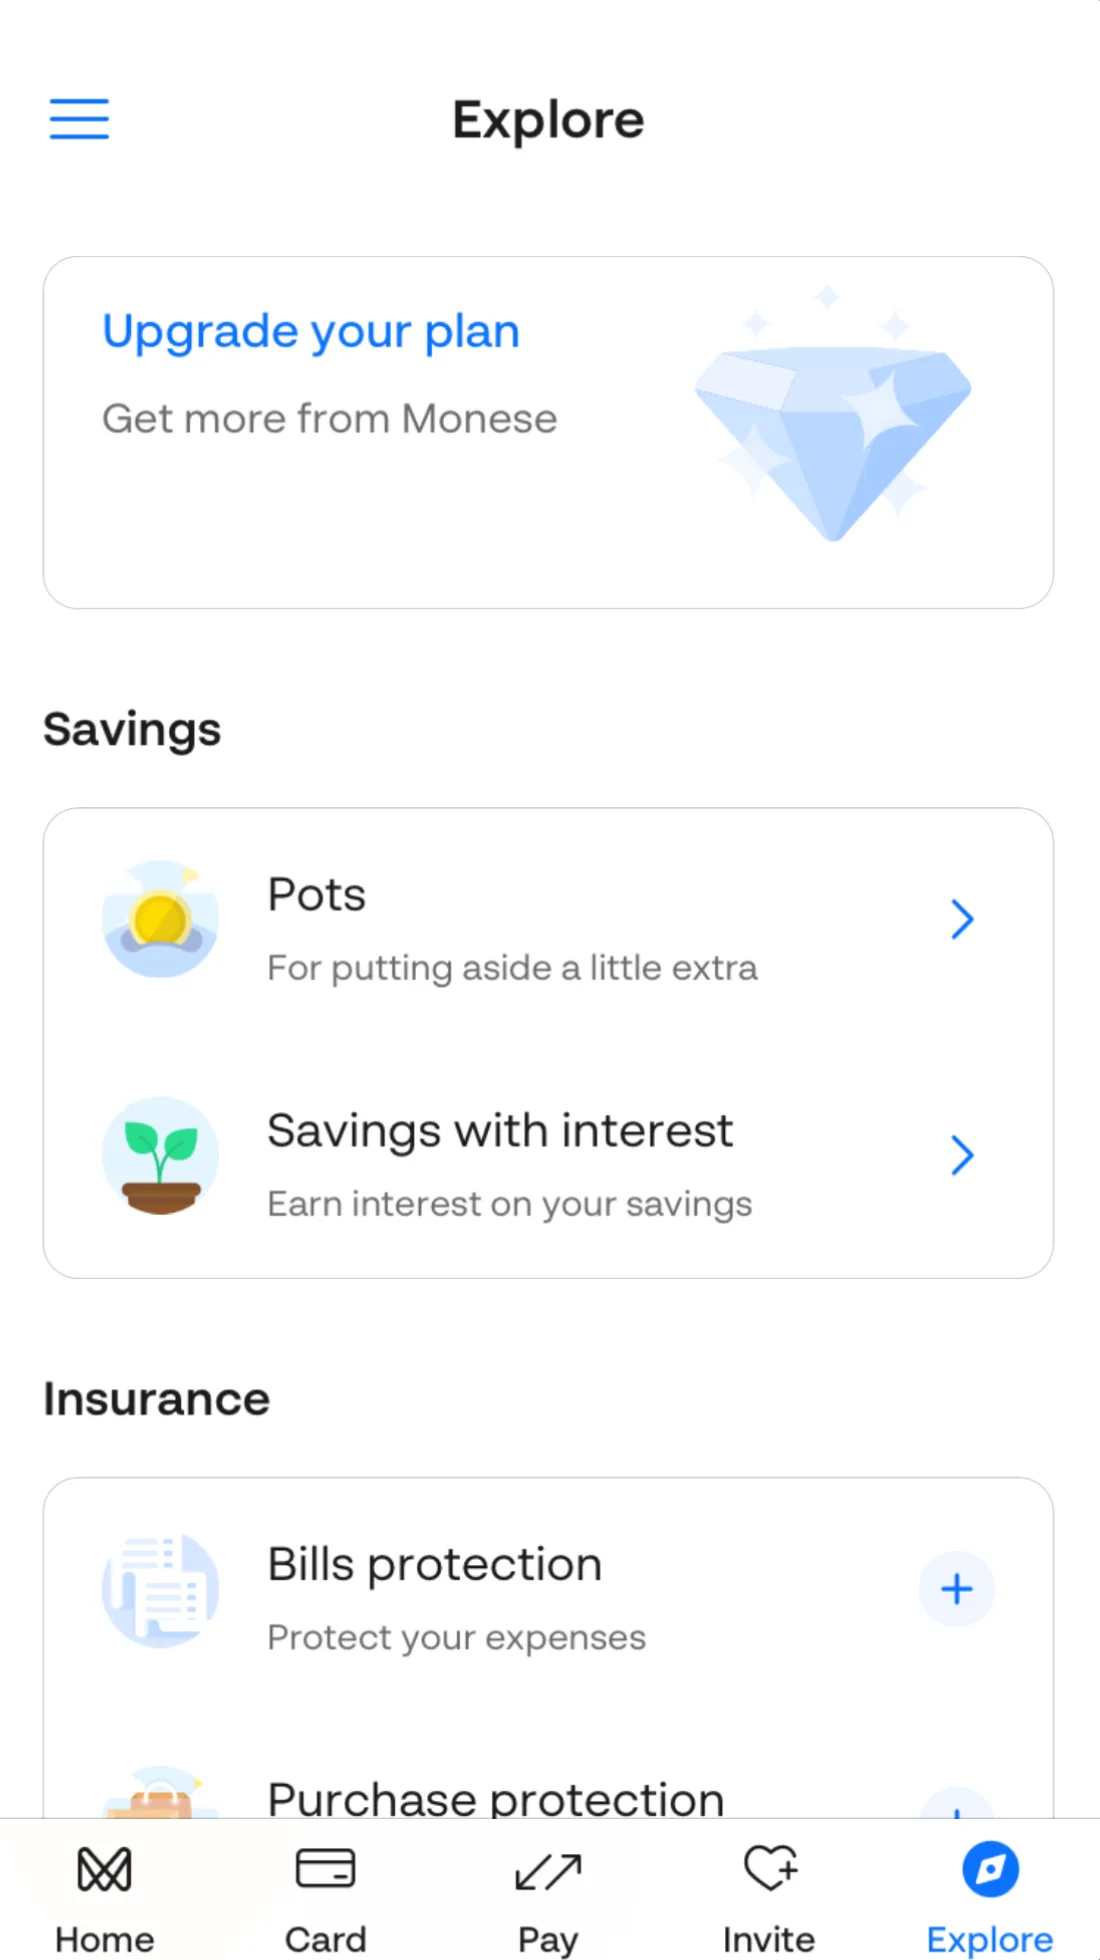
- Savings pots. Set aside money in up to 10 different pots to keep it separate from your day-to-day spending.
What are the different Monese plans?
Monese offers 4 different price plans. One of them, the Pay as you go plan, has no monthly fee, while the other 3 (Everyday, Cashback and Premium) charge a monthly fee but offer a greater range of features.
Note that all accounts can be held in GBP, EUR and RON and all offer money pots to help you set aside cash for different savings goals. Additionally, all plans give you access to the Credit Builder feature. You can also link any of the 4 account plans to your Avios account (if you have one) and earn Avios every time you spend with Monese, as well as link PayPal to your account.
Pay as you go plan
This free plan is a pretty basic account, and while transfers to other Monese accounts are free of charge, you will pay a fee to receive and send money to other accounts and send money abroad.
Fees will also apply to ATM withdrawals, cash and debit card top-ups and when you spend on your card abroad. There’s also a fee for the delivery of your first card (this is waived with a £100 first deposit).
Everyday plan
This is a paid-for plan but in return for your monthly fee, you’ll receive a greater range of benefits. These include:
- Free Monese to Monese transfers
- 2 free transfers to other accounts each month
- Free transfers in
- A small fee to send money abroad
- Free virtual debit cards
- A small fee for debit card top-ups
- A small fee for spending on your card abroad
Cashback plan
In return for a higher monthly fee, you’ll receive the following benefits:
- Free Monese to Monese transfers
- 10 free transfers to other accounts each month
- A small fee for international transfers
- Free virtual debit cards
- A fee-free monthly limit for cash top-ups
- A small fee for debit card top-ups
- A small fee for spending abroad
- A fee-free monthly limit on ATM withdrawals
- Cashback on spending.
Premium plan
This is a step up from the other plans so requires a higher monthly fee. In return, you’ll receive the following benefits:
- Free Monese to Monese transfers
- 200 free transfers to other accounts each month
- Free international transfers to other accounts
- Free virtual debit cards
- Free debit card top-ups
- A higher fee-free monthly limit for cash top-ups
- Fee-free spending abroad
- A higher fee-free monthly limit on ATM withdrawals
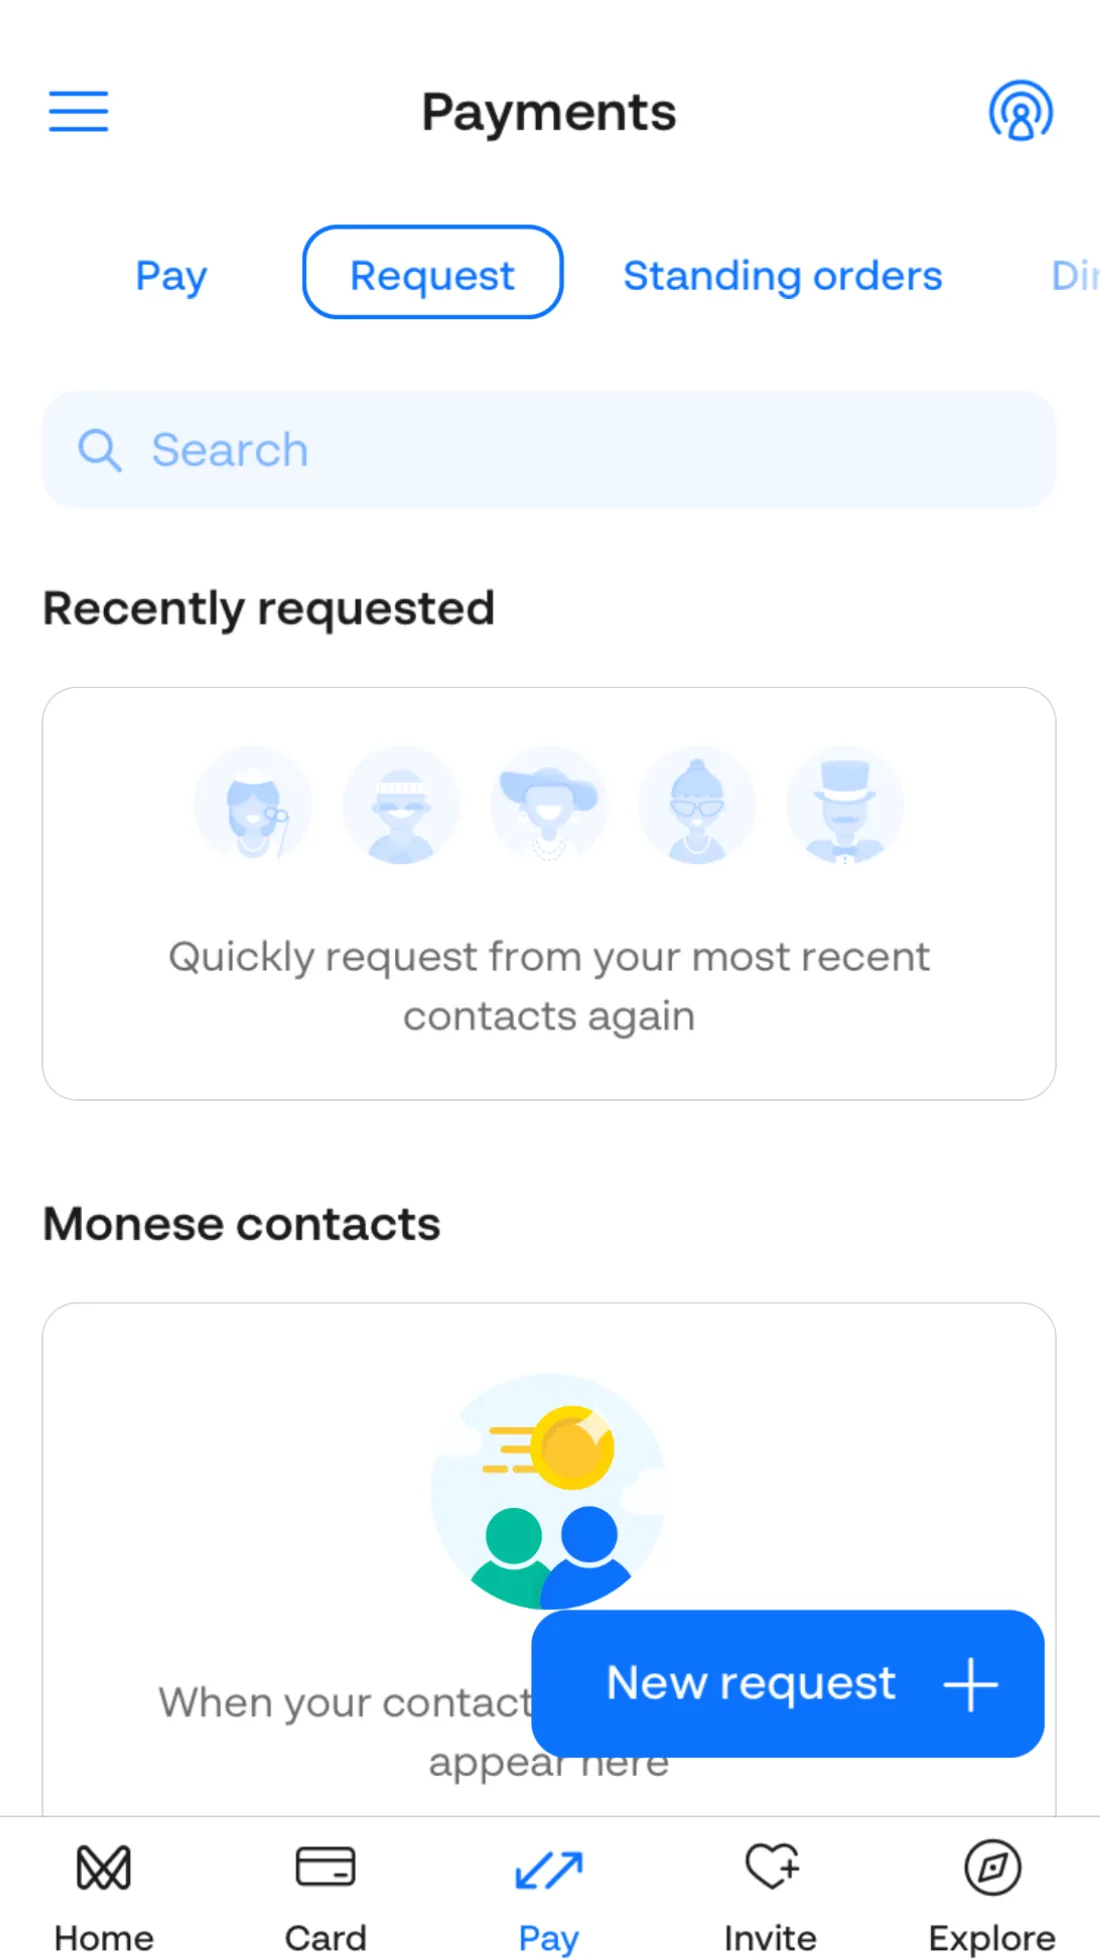
What does the Monese app look like?


How can I transfer money with Monese?
- UK bank transfers. Pay friends, families or bills with bank transfers. Monese uses the Faster Payments Service and says that these money transfers are typically instant.
- Foreign transfers. Transfer money abroad into 19 different currencies. Monese uses the “interbank rate”, much like Revolut. The delivery time for your money depends on the processing times of the receiving bank. Depending on the currency you’re sending and the time (try sending before 4pm), your transfer should take between 2-4 business days.
- Foreign transfer from Eurozone account. If you’re transferring money to someone with a Euro account through a SEPA payment, then it should reach them the same day or by the next working day.
- Direct debits. Set up a direct debit and automatically pay for utilities and services. Whether it’s your gym membership, phone contract, or your electricity bill – this way you won’t forget to pay the rent this month.
- Standing orders. Set up a standing order (or “Recurring Payment”) to make routine payments for a specified amount, payee and date – all managed in-app.
- Pay your contacts. Make payments to friends and family – straight from your phone’s contact list. See who’s already a Monese user, and to whom you’ll be able to make an instant payment.
Using Monese abroad
Monese has the option of opening an account across Europe making it easier to spend money in the UK and on the continent. Being able to switch instantly between your UK and European accounts means you’ll be able to spend abroad like a local. You can also open an account in Romanian lei.
Is Monese safe?
As a current account provider, Monese makes security a priority. To register it requires your address, a passport photo and video identification.
Your account is protected by a passcode which can be changed at any time, and you are logged out after 20 minutes of inactivity. If your phone or card is stolen, customer service is available Monday to Saturday during working hours.
Monese is registered with the FCA (Financial Conduct Authority) and is authorised to deal in electronic money, but isn’t technically a bank. In practical terms, this means that your money is held in a segregated account that Monese can’t touch (even if it were to go bust), but it isn’t protected by the Financial Services Compensation Scheme.
What do customers say about Monese?
77% of customers we surveyed in 2026 would recommend Monese to a friend.
It's primarily utilised by customers as a convenient secondary or travel account rather than a main bank. Users appreciate its ease of use, functionality abroad, and the ability to utilise pay points in the absence of traditional branches.
However, the provider faces significant criticism regarding its fee structure, particularly charges for transferring money. Several users also reported poor customer service and a clunky app experience, suggesting it may not be robust enough for primary, day-to-day banking.
AI-generated summary from the text of customer reviews on Finder.
Pros and cons of Monese
Pros
- UK current account that does all you can expect, including direct debits and standing orders.
- Fast and easy set-up (no credit check needed).
- Colourful app that is easy to use, allows you to categorise your transactions and freeze the card if you lose it.
- Can open both a UK and European account and switch instantly.
- Offers a Credit Builder feature.
Cons
- Depending on the plan, you may incur a range of fees, including for cash top-ups, foreign spending and ATM withdrawals.
- To avoid these fees you'll need to pay for the more expensive Premium plan.
- All plans charge a fee for card delivery, unless you make a £100 first deposit.
- No physical branches.
Customer service information for Monese
| Email support | |
|---|---|
| Telephone support | |
| In-app or live chat | |
| Contact form | |
| Branch support |
Our verdict: Is an account from Monese worth it?
Monese is great for travellers and works well if you are looking to set up an account quickly in another country. Depending on the plan you pick, you may benefit from low or no fee card payments and some fee-free ATM withdrawals abroad, something you can only dream of with a traditional bank.
However, to get the most out of your account, you’ll need to pay a monthly fee and there are far more attractive options out there. Competitors Monzo and Starling are similar but have a full banking licence and offer more features, including overdrafts and fee-free spending abroad – even if you pick a free account.
Finally, if you regularly need to make international money transfers and hold multiple currencies, you should check out Revolut, which beats Monese by allowing you to hold and transfer around 30 different currencies for free. Get started by downloading the app.
Frequently asked questions
-
In three main ways
- Treasury income. Some deposits are held by the Bank of England where they gather interest.
- Interchange income. The fee that Monese takes from card transactions.
- Fees and commissions. Fees Monese charges for certain payments. It also makes money from upselling Monese accounts, which require a small fee to maintain.
-
Easy, head to your existing account and transfer money from there or go to a PayPoint or Post Office and pay money in manually for a small fee. You can find your account details easily on the Monese app.
-
No. Monese won’t currently allow you to cash cheques.
-
The answer depends on how you deposit your money. If you use the Post Office, the maximum deposit per day is £500. If you use PayPoint deposits, you can deposit a maximum of £249 per transaction but a total of £500 per day.
-
There’s no limit to the number of times you can withdraw money. However, the daily maximum that can be withdrawn is £300.
-
Upgrading is simple. Go to the account menu and choose ‘My Plan’ to upgrade. You’ll need to have enough funds on the account to cover the 1st monthly fee. Should you wish to downgrade again, you can do so at any time.
-
There are currently 4 main ways to top up your UK Monese account:
(1) Cash top ups
Go to a Post Office or PayPoint location. Give them your debit card and the money you wish to deposit. With Monese Pay as you go and Everyday plans, you pay a 3.5% fee. With the Cashback plan you have a fee-free limit of £100 a month and with Premium this rises to £1,000. Funds will be available on your account in a couple of days.
(2) Bank transfers
To transfer funds into your Monese account from another UK bank, you will need your Monese account number and sort code. Find these details in the app.
(3) IBAN transfers
You can pay money into your Monese UK account from outside the UK by using the following details:
Recipient / Beneficiary: Monese LtdIBAN: EE047700771001660150
BIC/SWIFT: LHVBEE22
Comment / Reference to beneficiary / Reference: (Your Monese ID e.g. M12345) (You can find your Monese ID inside the Monese mobile app. Android users will find it via the side menu. iOS users will be able to find it in the ‘Account’ section of the app.)
You also need to ensure your Monese ID is included as a reference.
(4) Instant debit card top up
Go into the app, head to the ‘Instant Top Up’ section and enter your debit card’s info.
Debit card top ups are only free with the Premium plan. Otherwise you’ll pay 2% with the Pay as you go plan and 1% with the Everyday and Cashback plans. Any foreign exchange will be done by the issuer of the debit card used and an additional 2% fee applies (excluding the Premium plan). Also, note that credit cards will not work with this feature.
You will also soon be able to top up with Apple Pay or Google Pay.
-
The Monese UK account maximum balance is £40,000.
-
Yes, there are other banking apps out there. We have even created a guide on some of the better known alternatives.
-
Acquired by Monese in late 2021, Trezeo was a peculiar hybrid between a credit card, a current account and a budgeting app. It was essentially a digital account that connected to your regular current account through Open Banking and managed your income for you.
Based on your previous earnings, an algorithm calculated how much you make per week and transformed that into a weekly paycheque.
If you made more, it would put the extra money aside; if you earned less, it would take the rest from your savings or, if you don’t have any, it would offer you an advance. In a way, it was like having a regular salary.
Trezeo was meant to be used mostly by freelancers and gig economy workers (such as Uber drivers or Deliveroo couriers) whose income can be a bit bumpy.
How did Trezeo work?
In order for Trezeo to work, you needed to have all your income paid into your Trezeo account (it had its own account number and sort code).
Trezeo then paid your average weekly salary into your regular current account and kept the rest in your Trezeo account. By doing so, it provided the following services:
- Income smoother. You’d know exactly how much you’d get every week and how much you could afford to spend.
- Savings account. Trezeo helped you save by automatically putting aside any extra cash you earned. You didn’t earn any interest on your savings, but Trezeo was looking into offering it (prior to acquisition). You could get your savings back into your regular current account anytime.
- Credit. It didsn’t automatically come with the membership and you needed to apply for it. If you were accepted, Trezeo would top up your paycheque on those weeks when you earned less than your average, even if you didn’t have any savings aside.
You could keep all this under control directly from the Trezeo app.
Michelle Stevens is a deputy editor at Finder, specialising in banking, credit, loans and mortgages. She has a journalism degree from the University of Sheffield and has been a journalist for 15 years, writing on topics including fintech, payment systems and retail. In her spare time, Michelle likes to travel, explore new foodie experiences and attempt to improve her own culinary skills. See full bio
- Banking
- Mortgages
- Credit
- Fintech
- Payments
- Loans
Nick Renaud-Komiya has been a writer and reporter for nine years, covering a range of consumer issues from energy suppliers to banking and mortgage issues. He enjoys helping people take control of their personal finances and better understand their consumer rights. Nick’s consumer writing and money journalism has been featured in a range of outlets including MoneySavingExpert.com, The Sunday Mirror, The Independent and Money.co.uk. Outside of work Nick enjoys cooking and collecting old David Bowie merch. See full bio
More guides on Finder
-
Starling promo, discount and referral codes for November 2026
New to Starling? See if you can keep some more money in your pocket with our promo codes and special offers.
-
Kroo review: A UK-based social banking app
Discover whether Kroo’s account and card could work for you.
-
Revolut invite & promo code offers for November 2026
New to Revolut? Check out what it offers and see if you can save more with our discount codes and deals.
-
Nationwide current accounts for November 2026
Nationwide has one of the most competitive current account offers available on the market. Discover their features, compare options and apply.
-
Barclays current accounts for November 2026
Barclays offers a full range of current accounts with different sets of perks and rewards. We compare and contrast them to help you choose the right one.
-
Halifax current accounts for November 2026
Compare Halifax current accounts to find the best option for you.
-
smile app review
The UK’s first digital bank, smile is known for its role in past technological innovations in banking. While it was on the cutting edge of banking in the late 90s, is it still today?
-
The Co-operative Bank current accounts for November 2026
With a current account from The Co-operative Bank, you’ll get access to worldwide travel insurance from AXA, UK and European breakdown cover from RAC, everyday rewards and the option to have a greater degree of control over your spending.
-
Bank of Ireland current accounts for November 2026
Ireland’s largest financial services group offer a variety of eye-catching features with their current accounts, including cashback rewards.
-
Danske Bank current accounts for November 2026
Copenhagen-based Danske Bank has a current account for everyone, from 11-to 17-year olds to those wanting fee-free cash withdrawals in non-sterling currencies. You can earn a £7 cash reward paid into your account each month, zero interest and fees on the first £100 of an overdraft and favourable interest rates on personal loans.