Having an offer accepted on your first home is an exciting milestone, but it’s also the start of a complex multi-stage process. Managing a purchase involves many moving parts, and recent government research reveals average UK transaction times have increased by 60% since 2007.
Because the process involves lenders, brokers, solicitors, surveyors, estate agents, and the sellers, first-time buyer mortgages frequently stall. Working with proactive specialists such as Habito by Monzo, Tembo or L&C Mortgages can reduce unnecessary delays and admin. It’s impossible to completely eliminate external delays but an organised approach helps keep your purchase moving forward.
Why do house purchases stall after an offer is accepted?
Typically, the most recent government research and insights from industry bodies like Propertymark identify 4 primary bottlenecks that slow down transactions:
- Conveyancing capacity. Multiple industry reports highlight capacity constraints among conveyancers and delays from local authorities in returning property searches.
- Lender processing and document requests. Mortgage lenders may request additional bank statements, proof of gifted deposits, or clarification on self-employed income.
- Property survey discoveries. Uncovering unexpected issues (such as damp, structural movement, or roof defects) often requires negotiating repairs or getting specialist quotes before transactions can proceed.
- Property chain dependencies. Even though as a first-time buyer you may not have a property to sell, purchases typically take longer when you are part of an interconnected property chain, as progress depends on the slowest link.
Research from the UK government found that it takes an average of 120 days for a purchase to complete once an offer is accepted. And data from the HomeOwners Alliance backs this up, indicating that conveyancing alone in England and Wales typically takes around 12 to 16 weeks to reach the exchange of contracts.
Key property purchase delay factors
| Stage | Common cause of delay | How to prevent delays | Typical timeframe |
|---|---|---|---|
| Mortgage | Missing documents, lender valuation backlogs, underwriting queries. | Submit all certified financial documents immediately upon offer acceptance. | 2 to 6 weeks |
| Conveyancing | Local authority search backlogs, slow enquiries, unreturned seller contracts. | Instruct a solicitor early, pay search fees promptly, and complete ID checks immediately. | 8 to 12+ weeks |
| Survey | Access delays with the seller or finding defects requiring specialist survey reports. | Book your detailed RICS survey as soon as the mortgage application is submitted. | 1 to 3 weeks |
| Property chain | Delays or collapsed sales higher up or lower down the buying chain. | Request regular chain updates from the seller’s estate agent. | Variable |
How to keep each stage of the property purchase moving
Here are four ways you can ensure you’re on top of everything to give you the best chance of a smooth property purchase as a first-time buyer:
Accelerating your mortgage application
- Prepare documents in advance. Have 3 months of bank statements and payslips, your P60, proof of address and ID, along with details about your deposit. If you’re self-employed, get at least 2 years’ SA302s or self-assessment filings.
- Handle gifted deposit paperwork early. If family members are gifting you money for your deposit, ensure they sign a gifted deposit letter and provide proof of ID and funds to satisfy anti-money laundering (AML) checks.
- Respond to lender queries. Check your email daily for direct queries from your lender or those forwarded by your mortgage broker and get back the requested details as soon as you can.
Streamlining conveyancing legal work
- Instruct your solicitor immediately. Look to do this straight away once you’re in a position to make an offer, don’t wait for the formal mortgage offer before appointing a legal representative.
- Carry out property searches. Local authority, environmental, and water searches can take anywhere from 10 days to 6 weeks depending on the council. Paying your conveyancer search fees upfront prevents early friction.
- Complete onboarding forms digitally. Choose conveyancers who offer digital ID verification and online portals can help avoid any postal delays.
Coordinating property surveys
- Differentiate valuation from survey. Remember that a lender’s valuation is designed solely to protect the bank’s investment, not to assess the structural condition of the property.
- Book early. Arrange a RICS Level 2 (Homebuyer Report) or Level 3 (Building Survey) as soon as your mortgage application is underway.
- Pre-arrange access. Ask the estate agent to confirm access dates with the seller or sitting tenants to avoid delays so a valuer or surveyor doesn’t have to reschedule.
Consider an integrated service
- How it works. Rather than treating your mortgage, conveyancing, and survey as completely separate tasks (meaning managing the timelines for 3 separate services yourself), making them connected parts of one journey helps ensure nothing falls through the cracks.
- Why it keeps things moving. Instead of sending emails and documents back and forth between a separate broker, solicitor, and surveyor, an integrated service like Habito Plus or Tembo One brings all three under one roof. You deal with a single team that knows your case, you get a personalised quote upfront, and you don’t find yourself answering the same question on 5 different forms!
- The realistic limits. While bringing services under one roof eliminates unnecessary chasing between separate firms, first-time buyers should remember that no service can bypass external delays, such as local authority search backlogs or property chain issues.
Can an all-in-one home-buying service reduce delays?
Yes, this is possible. Some modern brokers such as Habito and Tembo offer services like Habito Plus and Tembo One, which combines all 3 key elements (first-time buyer mortgage advice, conveyancing support, and a RICS-accredited surveyor).
Or, more traditional brokers like L&C Mortgages have a conveyancing service powered by My Home Move Conveyancing and Conveynext (although this doesn’t include surveyor support).
There’s no guarantee these packaged services will definitely be quicker. However, because everything is managed together, it’s far less likely that you’ll experience avoidable delays due to common problems like miscommunication or a lack of attention to detail.
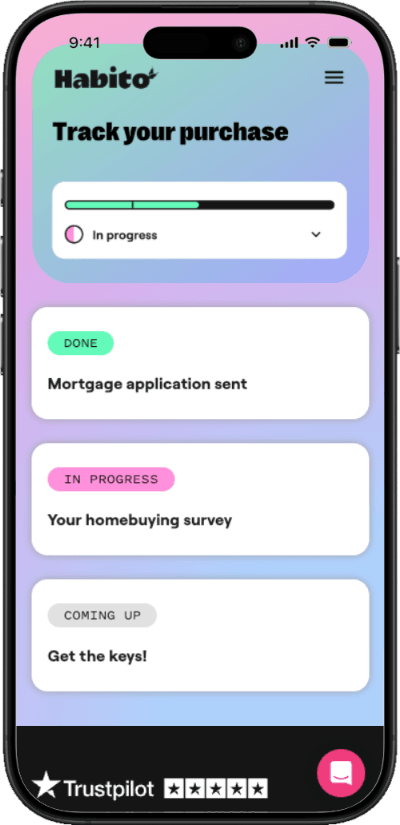
Habito Plus’s clear strength is expert-guided coordination: Habito supports buyers from mortgage application to completion while staying in contact with both the customer and conveyancer.
Speed advantages of using a complete service

Key benefits of a complete home-buying service include:
- One point of contact. Keep your mortgage broker, conveyancing support team, and surveyor aligned within one communication loop.
- Eliminates duplicate admin. You submit personal and property details once, rather than onboarding with 3 separate businesses.
- Pricing transparency. Some options like Habito Plus offer a clear, personalised quote upfront, making your costs predictable from the outset without needing to source quotes and negotiate across each area.
While joined-up coordination eliminates unnecessary chasing between separate firms, first-time buyers should bear in mind that no service can guarantee completion timelines or prevent external market delays. Factors like local authority search backlogs, complex legal title queries, lender underwriting checks, and property chain disruptions remain outside any single provider’s direct control.
"When my wife and I were buying our first home, the surveyor we used had been referred to us by friends, and the solicitors by our lender. The surveyor was fantastic but the solicitors were pretty uncommunicative. Whenever there were delays, our solicitors blamed the seller’s solicitors, and vice versa. The estate agent had stepped back by this point, so we felt a bit stranded. It was hard to know what was really going on, and we were navigating the whole thing for the first time. Friends and family sympathised but all rolled their eyes in a knowing way at the subject of solicitor delays. If I was giving advice to my younger self, I’d say to stay on top of the solicitors, surveyor and lender, or get somebody to do all that for you."
First-time buyer purchase progress timeline and checklist
If you want to track and manage everything yourself, here’s an outline to follow to help you keep on top of all the moving parts during a house purchase once you’ve had an offer accepted:
- Day 1. Gather all your relevant personal details (and for any other applicant). Formally instruct your conveyancer and complete your ID verification. Pay search fees to your conveyancer so local searches can be ordered immediately.
- Week 1. Submit all financial evidence to your mortgage broker to progress from Agreement in Principle (AIP) to full application. Book a RICS-accredited property survey (you choose the level needed).
- Week 2. Follow up with your conveyancer to verify that draft contracts have been received from the seller’s solicitor.
- Week 3. Confirm the mortgage valuation has been completed and monitor underwriter approval.
- Week 4. Review the survey report and discuss any major defects with your surveyor.
- Week 6+. Request a weekly summary from your conveyancer listing outstanding legal enquiries, search status, and mortgage offer confirmation.
Bottom line
Managing a first-time buyer house purchase requires organisation, clear communication, and consistent follow-ups across multiple areas. Certain external factors can extend timelines, but first-time buyers can avoid self-inflicted delays by submitting documents promptly, instructing conveyancers early, and setting clear expectations with estate agents and mortgage lenders.
Integrated services like Habito Plus offer a practical way to streamline your admin by coordinating mortgage advice, legal support, and RICS surveys under one roof. Or options like L&C Mortgages can cover the advice and conveyancing (without the survey). Part of your decision will likely come down to how hands-on you want to be when it comes to managing the progress of your house purchase.
Frequently asked questions
What is the fastest realistic timeframe to buy a house in the UK?
Because every sale relies on third parties, there is no magic shortcut or guaranteed completion timeline.
The most effective way for first-time buyers to shave unnecessary weeks off the process is to eliminate self-inflicted admin delays: have all certified financial records to hand before making an offer, instruct a solicitor immediately upon offer acceptance, and establish early on who is accountable for each upcoming milestone.
Can you run legal conveyancing and a mortgage application simultaneously?
Yes, and doing so in parallel rather than one after the other is essential for keeping momentum. Instead of waiting for a formal mortgage offer before appointing a legal representative, get legal onboarding done and pay for property search fees right away.
Ensure your conveyancer and mortgage broker are actively sharing updates so lender conditions are cleared while legal searches progress. Using a joined-up home-buying service can help align these parallel workstreams and reduce admin handoffs, though external hold-ups like council backlogs will still take their natural course.
How do I pinpoint exactly who is stalling my home purchase?
Before making broad progress calls to everyone involved, diagnose where the specific bottleneck sits. If underwriters are evaluating income evidence, check in with your mortgage broker; if property title enquiries or local searches are taking time, request an update from your conveyancer; if scheduling access for an inspection is taking too long, speak with the estate agent handling the sale.
If you're unsure, ask your point of contact for a status update showing the specific next action, the person responsible, and the expected timeframe.
Which mortgage brokers can arrange a RICS-accredited surveyor?
Habito Plus and Tembo One are examples of brokers that offer an integrated service that can coordinate whole-of-market mortgage advice, conveyancing support, and a RICS-accredited surveyor.
First-time buyers should also compare what's included in package quotes against arranging services separately. Also, some other brokers like L&C Mortgages can bundle in conveyancing, but not surveyor services.
How long do local authority conveyancing searches take, and can buyers speed them up?
Search times vary depending on your local authority (ranging from 5 working days to over 8 weeks in busy councils). While first-time buyers cannot force a council to work faster, you can prevent self-inflicted delays by instructing your solicitor and paying search fees on the day your offer is accepted.
Will an unexpected property survey result delay my formal mortgage offer?
It can. If a RICS Level 2 or Level 3 survey uncovers structural movement, damp, or roof defects, your lender may pause underwriting or request specialist contractor quotes before approving the loan. To minimise delays, book your survey as soon as your mortgage application is officially underway.
How can I chase my conveyancer or broker without causing friction?
Calling daily can slow down legal work. Instead, schedule a structured weekly check-in and ask 3 specific questions:
- What is the exact next step?
- Who is responsible for it?
- What is the target date?
Using an integrated home-buying service can reduce the administrative burden of chasing multiple companies individually, as mortgage guidance, legal support, and survey arrangements are coordinated through one central route.
What house-buying delays are completely beyond a buyer's control?
Several external factors can extend transaction timelines regardless of how much you prepare. These can include slow local council search departments, delays in receiving leasehold management packs from freeholders, complex legal title queries, and disruptions within an interconnected property chain.
What is the relationship between Habito and Monzo, and what does Habito Plus cover?
Habito acts as Monzo's mortgage and homeownership experts, helping buyers compare deals online. Habito Plus expands on this by combining whole-of-market mortgage advice with legal conveyancing support (delivered by a vetted panel of regulated conveyancers) and RICS-accredited property survey coordination.
Buyers get a clear, personalised quote upfront, just paying an initial deposit of £999, which ensures total costs are transparent before you commit.
What should I do if the seller's solicitor is delaying the conveyancing process?
If progress stalls because the seller has not answered legal enquiries or returned property forms, your conveyancer's options are limited to formal email chases. To break the stalemate, contact the estate agent who negotiated the sale.
Estate agents are financially motivated to reach the point of exchange and can directly nudge the seller to complete their paperwork or contact their solicitor.
Sources
George is a deputy editor at Finder. He has previously written for The Motley Fool UK, Nasdaq, Freetrade, Investing in the Web, MoneyMagpie, Online Mortgage Advisor, Wealth, and Compare Forex Brokers. He's focused on making personal finance and investing engaging for everyone. To do this he draws from previous work and his Level 4 Diploma for Financial Advisers (DipFA), sharing what he’s learnt. When he’s not geeking out about money, you’ll find him playing sports and staying active. See full bio
- Investing
- Personal finance
- Tax
- Pensions
- Mortgages
- Cryptocurrency
More guides on Finder
-
Mortgage, conveyancing and survey packages for first-time buyers explained
Discover how integrated home-buying packages work, how pricing compares vs paying for services individually, and decide whether to bundle your mortgage, legal work, and property survey into one.
-
How to get a mortgage as a first-time buyer
Every first-time buyer’s journey will look a little different, but here’s a step-by-step guide to the typical process for getting a mortgage.
-
Should I use a mortgage broker or go direct to a lender?
We go head-to-head in 8 key categories to find out whether it’s worth using a broker.
-
What insurance do UK first-time home buyers need?
What home buyer insurance is mandatory, what’s optional, and how to choose the best insurance deal as a first-time buyer.
-
Can a single person get a mortgage?
While it can be trickier than buying with someone, it’s absolutely possible to get a mortgage as a single person. Here’s what you need to know.
-
I’m a first-time buyer… How much can I borrow?
Looking to get on the property ladder, but not sure if you can afford it? Here’s what you need to know.
-
How to get a first-time buyer mortgage with bad credit
Learn how to secure a mortgage as a first-time buyer with bad credit by mastering essential financial strategies and exploring low-deposit options.
-
11 common first-time buyer mortgage mistakes (and how to avoid them)
Discover how to sidestep common mortgage pitfalls and avoid the expensive delays that often catch first-time buyers off guard.
-
Help and advice for first-time buyers getting a mortgage
Want to know how to choose the right mortgage as a first-time buyer? Our guide will give you everything you need to know to find the help and advice you need.
-
First-time buyer definition: Who qualifies and who doesn’t?
The definition according to the UK government.