Best ways to spend travel money in South Africa: Debit and prepaid cards

Learn more about the best card to use, if you should use a UK debit card and other ways to take spending money to South Africa.

If you’re preparing for a trip to South Africa, whether it’s for pleasure or business, it pays to find a travel money product that’s going to let you spend and withdraw South African rand cheaply.

Key takeaways

  • The currency in South Africa is the rand.
  • ATMs are widely available but withdrawal limits can be low.
  • Choose a debit card with low fees (or no fees) for travel from our top picks.

Low-cost travel money options for South Africa

Low fees + sign-up bonus

Promoted
Revolut logo

T&Cs apply

£20 welcome bonus
  • Pay like a local with excellent exchange rates
  • Send money in 29 currencies
  • Cashback on hotel bookings

No overseas fees card & budgeting

Promoted

Monzo logo

T&Cs apply

Earn interest on your holiday money with a savings pot
  • Make fee-free cash withdrawals
  • Spend abroad with no fees
  • Split costs with friends in seconds

No FX fees

Promoted

Wise logo

T&Cs apply

More than 150 countries
  • Open an account in minutes
  • Use in more than 150 countries
  • 2 free cash withdrawals per month

Although plastic is widely accepted in South African towns and cities, it’s unrealistic to think you can get away with just making card payments in South Africa. As you’ll need access to cash, this means ATM withdrawal fees should be a factor in your comparison of travel money options for South Africa.

  • Tip: Make sure you tell your card issuer about your travel plans. Credit card fraud is common in South Africa and your bank may block your card if you make a card payment or withdrawal in South Africa.

How much rand should you bring on your trip?

High summer season premiums will add to the cost of your trip to South Africa, but the cost of living and travel varies depending on where you are in the country. In smaller towns, South Africa is surprisingly affordable. Further south and especially in touristic places like Cape Town and Johannesburg, it can be very expensive. If you go to South Africa during high season (December to February) expect to pay a premium for everything. Off-season, prices drop dramatically.

Find out some typical holiday prices in Cape Town

Cape TownBudgetMid-rangeExpensive
sleepHostels
£15–£30 per night

2-star hotel

£30–£60 per night

5-star hotel

£80–£630+

food

Fast food

£4–£10

Dinner at a mid-range restaurant

£18 per person

5-star restaurant

£50+ per person

skydive

Boat trips

£7 per person

SkyDive Tandem – FreeFall Experience and Parachute Ride
£120–£200

Hot-air ballooning

£150–£200 per person

*Prices are approximate and are subject to change.

How travel cards, credit cards and debit cards work in South Africa

A quick summary of your travel money options in South Africa

Travel money optionProsConsiderations
Debit cards for travel
  • Protected by Chip and PIN
  • Access your own funds
  • The right card waives currency conversion and withdrawal fees
  • The wrong card charges currency conversion and withdrawal fees
  • Linked to your bank account which can be an issue if your card is stolen
Prepaid travel money cards
  • No currency conversion fee if you spend in right currency
  • Dual card account
  • Locked-in exchange rates
  • Higher exchange rates compared to Visa and Mastercard
  • Fees can apply (such as a reload fee, ATM withdrawal fee, inactivity fee, overseas ATM withdrawal fee)
Credit cards for travel
  • Some cards waive foreign transaction fees
  • Access to funds up to your credit limit
  • Extra features such as complimentary insurance and purchase protection
  • Fees and interest often apply to ATM withdrawals
  • Temptation to spend
Traveller’s cheques
  • Safer than cash
  • Can be easily replaced if lost or stolen
  • Photo I.D. needed to cash cheques
  • Inconvenient to cash cheques
  • Cost

This table is a general summary of the travel money products in the market. Features and benefits can vary between cards.

How the different travel money products work in South Africa

Using prepaid travel cards

If you use a prepaid multi-currency travel card, you can load it with British pounds and convert the funds to a supported overseas currency at a locked-in foreign exchange rate.

If you’re spending in a loaded and supported currency, you’ll save on currency conversion fees and be protected from fluctuating currency exchange rates. The currencies you can spend in will vary from card to card, but some allow you to add rand which means you won’t pay fees for spending on your card in South Africa.

Even if you don’t have the supported or local currency on your card, you should still be able to use your travel card wherever Visa or Mastercard is accepted, but a currency conversion fee will apply.

If your card is running low on funds, you can top up via an online transfer. It can take between 24 hours and 2 business days for funds to appear in your account, so avoid bleeding your account dry before topping it up again.

Benefits

  • No currency conversion fee. Find a travel card that lets you convert British pounds to South African Rand without paying extra for the currency conversion.
  • Dual card account. You get two cards when you apply for a travel card account, which will come in handy if one is lost or stolen while you’re on holiday.
  • Locked-in rate. The exchange rate is locked in when you transfer funds between currency wallets, protecting you from negative currency fluctuations.

Drawbacks

  • Exchange rate. Travel cards are subject to the card provider’s cash rate. This is higher than the exchange rate offered to Visa and Mastercard debit and credit cards. There are travel card providers that use the better-value interbank rate, but these products are not common.
  • Fees. You may pay fees when you use the card, either to load or reload funds, to withdraw from an ATM or to transact in a currency not already loaded on the card. Some accounts also charge an inactivity fee. Even if you use a travel card from a bank with an international ATM alliance, you could still incur an international ATM fee.

Using credit cards

A credit card can be a good way to access a higher line of credit, which can come in handy when making large or emergency purchases on your holiday. However, if the card isn’t designed for overseas use, you’re likely to rack up fees as you spend.

Benefits

  • Financial freedom. Unlike a prepaid card or debit card that deducts from your savings, a line of credit could come in handy when making large or emergency purchases overseas.
  • Rewards. Some credit cards come linked with a frequent flyer or rewards program, meaning you can earn points as you spend. Some cards even offer bonus points for purchases overseas.
  • Extra features. Credit cards often come with extra features such as complimentary insurance and purchase protection. If you’re travelling overseas, you’ll need insurance anyway, so getting complimentary cover through your credit card could save you time and money.
  • Some travel friendly options. Some credit cards are designed to be used overseas and won’t charge a foreign transaction fee when you spend on them.

Drawbacks

  • Foreign transaction fees. Some credit cards charge foreign transaction fees of around 3% per purchase. Look out for a credit card that waives these fees to keep your costs low.
  • ATM fees. Credit cards aren’t designed for ATM withdrawals, so you’re likely to incur a high cash advance fee when using your card for withdrawals overseas. You will also be charged interest from the moment you get your cash, making it expensive.
  • Temptation to spend. Having access to a line of credit might give you a false sense of financial security that tempts you to make unnecessary purchases. Remember that you have to repay every purchase (plus interest, in most cases) charged to your card.

If you’re thinking of using a credit card overseas, opt for one with low or no foreign transaction fees as well as other features, such as rewards or complimentary insurance that will benefit you on your trip.

Using debit cards

Most ATMs in South Africa accept Mastercard and Visa debit cards. While there are benefits to accessing your own funds overseas, there are some drawbacks that come with using your debit card in South Africa.

Benefits

  • Access your own funds. A line of credit can be good financial security, but accessing your own funds in your debit card gives you a more realistic idea of how you need to manage your travel budget.
  • Travel-friendly debit cards. While some debit cards will incur foreign transaction and ATM withdrawal fees, others are designed for overseas use and will avoid these costs.

Drawbacks

  • ATM withdrawal costs. Some cards still charge ATM withdrawal costs, so look out for cards that belong to an ATM alliance that won’t charge you when making withdrawals overseas.
  • Linked to bank account. If your card gets into the wrong hands, it can be easy for funds to be taken from your bank account.

Using traveller’s cheques

Traveller’s cheques are safer than cash. They can be replaced if lost and you need photo identification to cash your cheques. The downside is convenience and cost: You need to visit a bank in South Africa to cash your cheques. Different banks charge different commissions and the exchange rate can vary from bank to bank as well.

The South African rand

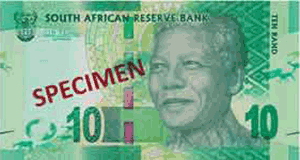
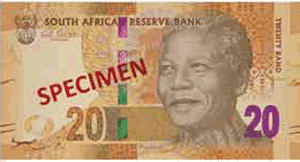
South African banknotes come in denominations of 10 rand, 20 rand, 50 rand, 100 rand and 200 rand. The coins available are 1 rand, 2 rand and 5 rand. Small coins are 5, 10, 20 and 50 cents. Prices are rounded down to the nearest 5 cents and the notes are easily distinguished by colour.

south-africa-10south-africa-20
south-africa-50south-africa-100
south-africa-30

Find cash and ATMs in South Africa

The main banks in South Africa are:

  • ABSA
  • Nedbank
  • FNB
  • Standard Bank
  • Bidvest
  • Capitec

What you need to know about withdrawing cash from a South African ATM

South African banks do not charge you to use their ATMs. So you can save on ATM withdrawal fees altogether by choosing a card that doesn’t charge for international ATM withdrawals.

  • ATM withdrawal limits
    The maximum amount you can withdraw from an ATM in South Africa is approximately 3,000 rand per withdrawal. You may be able to withdraw more than this if you visit a bank branch and supply photo identification to the teller. You can make multiple withdrawals up to your card provider’s daily withdrawal limit.
  • Getting your money changed in South Africa
    You may be approached to get your money changed by a street vendor in South Africa. Although the rates they can give you may seem attractive, there’s a good chance you’re going to get ripped off. Plus, there’s an inherent danger in flashing large amounts of money around on the street.
    Get your money changed at currency exchange offices, banks or make withdrawals from a reputable ATM. You may want to get a sum of money changed to rand before you leave the UK so you at least have a little bit of cash on you at the airport. ZAR is a frequently traded international currency and you may be able to find rates at home that are comparable to the rates you can get when you change your money when you arrive.
    Arguably, the best way to get South African rand is to make an ATM withdrawal. This transaction is subject to the interbank rate, plus a small margin from the card issuer – but some providers waive this. The interbank rate is the exchange rate banks and large financial institution use to buy and sell foreign currency. Changing cash on the street will give you the tourist rate, whereas using an ATM gives you something close to the interbank rate.
  • Use a mix of travel money options for the best result
    Take a mix of travel money options to transact in South Africa conveniently and cheaply. For example, take a credit card for emergencies, but keep your debit or prepaid card on hand for ATM withdrawals and day-to-day purchases. Many accounts cost nothing to open, so it’s not too much to ask to apply for a dedicated travel account. Consider your financial situation and how you’ll be spending your money on your trip to decide on the best combination.

Frequently asked questions

Our “Best for” picks highlight top options in specific categories based on our independent evaluation (see our full methodology), while “Promoted” tags indicate sponsored placements. Selected products may not suit everyone. We track selected market offers, which may not cover every product. Products are listed in no particular order unless specified, and inclusion or ordering may be influenced by popularity or commercial agreements. Most comparison table data is provided by Defaqto or sourced directly from providers. Always evaluate your own circumstances and consider independent advice before making major financial decisions.
Matthew Boyle's headshot

Matthew Boyle is a banking and mortgages publisher at Finder. He has a 7-year history of publishing helpful guides to assist consumers in making better decisions. In his spare time, you will find him walking in the Norfolk countryside admiring the local wildlife. See full bio

Matthew's expertise
Matthew has written 210 Finder guides across topics including:
  • Helping first-time buyers apply for a mortgage
  • Comparing bank accounts and highlighting useful features
  • Publishing easy-to-understand guides

More guides on Finder

Go to site