The UK's largest range of secured loans
- Loans from £1,000 to £2,500,000
- See your quote before you apply
- Quote won’t affect your credit score
If you’re looking to make major improvements to your home, consolidate large debts or fund a big-ticket purchase, a £50,000 personal loan could be just the trick. But when borrowing such a substantial amount, it’s important to be aware how to get a deal with the best terms. Failing to do so could cost you thousands over the duration of your loan.
Use our guide to compare £50,000 loans from a range of popular unsecured lenders. However, keep in mind that most lenders will not let you borrow £50,000 on an unsecured loan unless you’re already an existing customer and have an excellent credit rating. You may find that a secured loan is a better option.
Compare unsecured personal loans
See today's rates from across the personal loan market.
You can get a £50,000 loan for any worthwhile purpose, but popular reasons for a loan include:
When borrowing amounts as large as £50,000, you’ll almost certainly have to opt for a “secured loan”. With a secured loan you agree for an asset to be used as collateral against late or failed payments. More often than not, this collateral will be the equity in your property. As such these loans are often referred to as “homeowner loans” or “second-charge mortgages”.
Many lenders cap “unsecured” lending (which involves no collateral) at £25,000, but some big banks can offer up to £50,000. As these loans are more risky for lenders, they typically come with a higher rate and very strict eligibility criteria. If your credit file isn’t spotless, it’ll be extremely difficult to get approved and if you do get approved, the interest rate you’re offered might not be the most competitive. Additionally, it’s generally a requirement that you’re an existing customer of the bank – and ideally your relationship with the bank would go back a few years.
The amount you repay each month on a £50k loan will depend on both the length of your loan term and the interest rate you are charged. Compare the monthly payments for £50,000 personal loans using our table below.
| 5% p.a. interest | 10% p.a. interest | 15% p.a. interest | |
|---|---|---|---|
| 3-year term | £1,499 | £1,613 | £1,733 |
| 5-year term | £944 | £1,062 | £1,190 |
| 7-year term | £707 | £830 | £965 |
| 10-year term | £530 | £661 | £807 |
| 15-year term | £395 | £537 | £700 |
| 20-year term | £330 | £483 | £658 |
| 5% p.a. interest | 10% p.a. interest | 15% p.a. interest | |
|---|---|---|---|
| 3 years | £53,948 | £58,081 | £62,398 |
| 5 years | £56,614 | £63,741 | £71,370 |
| 7 years | £59,362 | £69,725 | £81,046 |
| 10 years | £63,639 | £79,290 | £96,801 |
| 15 years | £71,171 | £96,714 | £125,963 |
| 20 years | £79,195 | £115,803 | £158,015 |
The loan illustrations above use approximate, rounded figures, based on a flat interest rate. Longer-term secured loans are likely to have variable interest rates. If the rate goes down during the course of the loan, the monthly and overall costs would decrease. If the rate rises during the course of the loan, the monthly and overall costs would increase. Current interest rates are low compared to historical averages.
You can use our loan calculator to compare a range of £50,000 loans from popular lenders, based on monthly payment size and APR. Simply enter how much you want to borrow, how long you want the loan for, the value of your property and mortgage, then we’ll find you the loan that could best suit your situation.
When taking out a £50,000 secured loan, you may need to pay a number of fees, such as a lender’s fee or application fee, but this will depend on your specific lender or broker, and the nature of your loan.
You’ll also likely need to pay an appraisal fee, which covers the cost of the valuation that is done on your home to determine its value.
The minimum income requirements will vary depending on factors like the term of loan that you opt for. All lenders must be able to demonstrate that they are lending responsibly. In other words, they have been careful to make sure that you’d be able to afford the proposed repayment schedule, taking into account your income and outgoings. For example, if you’re an applicant with a £35,000 salary but relatively low regular financial commitments, you might actually stand a better chance than an applicant with a £50,000 salary and exorbitant monthly outgoings.
Ultimately your income is just one important part of the picture a lender will use to assess your case.
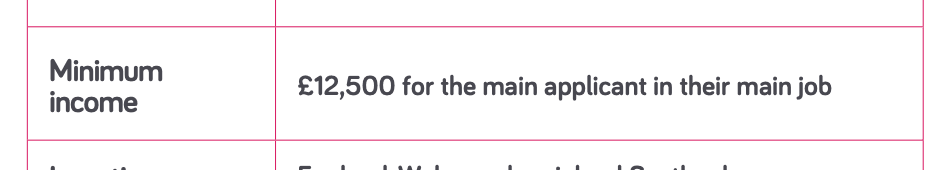
Loan companies might specify a minimum income requirement in their basic lending criteria (example below), but meeting these entry-level criteria means that your application can be assessed for approval, not that approval is guaranteed.
If you’re applying for an unsecured personal loan of £50,000, it’s very likely that you will need an excellent credit score. Different credit reference agencies use different scoring systems, but for Experian an Excellent score is 961 or higher. For Equifax, it’s 811 or higher and for TransUnion, 628 or higher. However, your credit score is just one factor on which your application will be assessed.
If your credit rating is not excellent, you may opt to use the equity in your home as security. In this situation, your credit score becomes a less crucial factor – but still a factor. The importance given to your credit score will vary from lender to lender, with some lenders specifically aiming to serve those with bad credit.
If you’re in the minority of people that can get approved for an unsecured loan of this size, then it could theoretically be in your account the same day. Realistically, larger loans are likely to get a bit more focus from actual human underwriters (that’s the people who stand between you and getting your loan) which can mean the process takes a couple of working days.
Secured loans more commonly take two to three weeks to arrange and draw down. Although there aren’t solicitors involved, a property valuation of some form will be required and the bank holding the first charge over the property will also need to give its approval.
These extra steps make secured loans a little slower, but the trade-off for many is access to lower rates and/or larger sums.
You can adjust your loan term in order to make your monthly repayments more affordable. Similarly, you can increase your monthly repayment in order to clear the loan in less time. As a general rule of thumb, spreading repayment over a longer timeframe normally makes for lower monthly repayments (but a higher overall cost). So it really depends on what you can afford to repay each month.
At a fixed annual rate of 5.5%, a £50,000 loan would take a little over 11 years to repay if your monthly repayment was £500. If you wanted to keep the monthly costs down, and paid £400 each month, it would take around 15.5 years.
Yes, most lenders will let you repay your £50,000 loan early, but you’ll generally need to pay an early settlement fee to do so. This fee will depend on the size of your loan, as well as how much you have remaining to pay off. Some lenders may also charge an additional fee for breaking the terms of your loan.
Here are some of the key factors that will matter to a lender weighing up the risk of lending to you:
Unfortunately, you’re unlikely to find a lender that’s willing to lend you £50,000 on an unsecured personal loan, so a secured loan is likely to be your best option when it comes to getting a loan of that size.
If your £50,000 loan is for a car purchase, you might have alternatives. Take a look at our guide to car loans and finance options to find out more.
Remortgaging, i.e. altering your mortgage deal and borrowing against the equity of your property, is a popular strategy for homeowners to get hold of larger lump sums. If you’ve got a lot of equity or can bag a low mortgage rate, this could prove more economical than a personal loan.
Borrowing £50,000 doesn’t give you as many options as you would if you were looking for a smaller amount. You’re almost certainly going to need a secured loan, and it might be worth going through a broker or a loan-matching service to find the right deal. Paying more interest than you need to on a loan of this size would be a very expensive mistake.
A secured loan can help you consolidate your existing debt by offering lower rates and more flexible loan terms.
A secured loan lets you use the equity in your house as collateral against the loan, even if you have bad credit. See how it works in our guide.
Browse our expert tips on how to get approved for a £70,000 loan and find the best rate deal possible.
Learn how to find the best deal on a £60,000 loan.
Discover how to find the best interest rate for an £80,000 personal loan, as well as how to boost your chances of being accepted for one.
Looking for a great deal on a £40,000 personal loan. We explore all your options and explain how to find the best one.
Find out how to pick out the best deal on a £30,000 personal loan. We weigh up all your options and how to find the best one.
Compare live rates, fees and eligibility criteria from a range of lenders to get the right loan for your needs at the lowest overall cost.
Find out how to maximise your chances of approval and apply online today. Compare live rates, fees and eligibility criteria to get the best loan for your needs.
