How much equity do I need to remortgage

The amount of equity you have in your home can determine your remortgaging options.
Think carefully before securing debts against your home. Your home may be repossessed if you do not keep up repayments on your mortgage.
When you choose to remortgage your existing mortgage, you should take into account the amount of equity you’ve built up in your home. If you don’t have enough equity, remortgaging could be a bad idea.

What is equity?

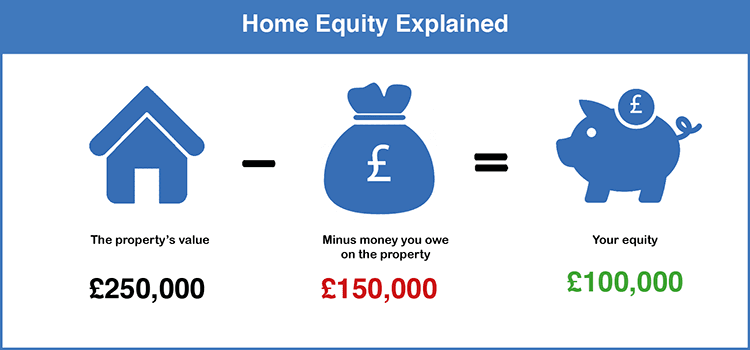
When you make payments towards the principal amount of your mortgage you build up equity in your home. The equity is the difference between your home’s value and what you have left to repay on your mortgage. This is the money you can expect to keep if you sell your home and repay your mortgage with the proceeds from the sale.

Graphic explaining home equity.

How much equity do I need when remortgaging?

Many loans come with a maximum loan-to-value (LTV) ratio of 95%, which means you cannot borrow more than 95% of the value of your home. What this also means is that if you wish to remortgage you must have at least 5% equity in your home.

To put yourself in a really good position to remortgage, you should have at least 20% equity in your home.

Applying for remortgaging with no equity is difficult unless you can get someone to be a guarantor, however, this depends on the lender and is fairly rare with majority of mainstream lenders.

Remember that lenders look at your equity as a means to assess risk. The more equity you have, the less of a risk you are to the lender and vice versa.

What if I don’t have at least 20% in equity?

When you choose to remortgage without at least 20% equity in your home, the lender is less likely to approve your application to remortgage. If you are approved, you will likely be charged a higher interest rate than you would be if you had 20% equity. This is because the more equity you have, the less of a risk you are to the lender.

Alternative options

Before comparing remortgaging options, find out how much equity you have in your home. If you don’t have a 20% deposit saved but aren’t far off the mark, it might make sense to wait until you’ve built up a higher amount of equity.

Alternatively, you can consider applying for a guarantor mortgage or applying with specialist banks that may have less stringent lending criteria for remortgage mortgages.

Our “Best for” picks highlight top options in specific categories based on our independent evaluation (see our full methodology), while “Promoted” tags indicate sponsored placements. Selected products may not suit everyone. We track selected market offers, which may not cover every product. Products are listed in no particular order unless specified, and inclusion or ordering may be influenced by popularity or commercial agreements. Most comparison table data is provided by Defaqto or sourced directly from providers. Always evaluate your own circumstances and consider independent advice before making major financial decisions.
Matthew Boyle's headshot

Matthew Boyle is a banking and mortgages publisher at Finder. He has a 7-year history of publishing helpful guides to assist consumers in making better decisions. In his spare time, you will find him walking in the Norfolk countryside admiring the local wildlife. See full bio

Matthew's expertise
Matthew has written 210 Finder guides across topics including:
  • Helping first-time buyers apply for a mortgage
  • Comparing bank accounts and highlighting useful features
  • Publishing easy-to-understand guides
More resources on Finder
Go to site