Roth individual retirement accounts (IRAs) and traditional 401(k)s are two types of retirement savings accounts that can help you grow your nest egg tax-free.
That said, the two accounts have some key differences regarding tax advantages, contribution limits and available investment options. Find out more about how these accounts stack up to see which is right for you.
Roth IRA vs. 401(k): A quick comparison
| Roth IRA | 401(k) | |
|---|---|---|
| Where to open | Brokerage, bank or other financial institution | Through an employer |
| Investment options | All assets are permitted inside an IRA except collectibles and life insurance The IRA custodian determines available investment options | Limited to investment options the employer has chosen, which are typically mutual funds and some exchange-traded funds (ETFs) |
| Income limits to contribute | Individuals filing as single and head of household. Contribute up to $7,500 if your 2026 modified adjusted gross income (MAGI) is under $153,000; individuals with a MAGI above $153,000 can contribute a reduced amount until contributions are phased out upon reaching a MAGI of $168,000(1) Married couples filing jointly. Contribute up to $7,500 each if your MAGI is under $242,000 per year; married couples with a MAGI above $242,000 can contribute a reduced amount until contributions are phased out upon reaching a MAGI of $252,000(1) | None |
| Contribution limits | $7,500 for those under age 50 $8,600 for those age 50 and over(1) | $24,500 for 2026 Employees 50 and older can contribute an additional $8,000 in catch-up contributions, for a total of $32,500 Employees 60 to 63 can contribute an additional $11,250 instead, for a total of $35,750(1) |
| Eligibility requirements | No age requirements, but you need earned income to contribute Income limits apply | Determined by plan sponsor |
| Who can contribute | Anyone can contribute, so long as your income doesn’t exceed a certain threshold | Anyone participating in an employer-sponsored plan |
| Tax advantages | Earnings grow tax-free Qualified withdrawals are tax-free | Contributions reduce your taxable income Earnings grow tax-free |
| Withdrawal restrictions | Withdrawals of earnings before age 59.5, or before the account has been open five years, generally incur income tax plus a 10% additional tax (exceptions apply)(2) Qualified withdrawals — made after age 59.5 once the account has been open at least five years — are exempt from both income tax and the additional tax on the full balance, including earnings(2) | Withdrawals before age 59.5 are subject to taxes and penalties If you separate from your employer in or after the calendar year you turn 55, withdrawals from that employer’s plan are taxed but not penalized(3) |
| Required minimum distributions (RMDs) | No RMDs | Traditional 401(k): required by April 1 of the year after the account holder turns 73 if born between 1951 and 1959, or 75 if born in 1960 or later Roth 401(k): no lifetime RMDs, effective for 2024 and later(4) |
| FDIC insurance | Roth IRAs that contain bank deposits such as certificates of deposit (CDs), savings accounts or money market accounts are insured up to $250,000 | None |
| SIPC insurance | SIPC insures cash and securities up to $500,000 at SIPC-member brokers(5) | 401(k) plan assets held in a brokerage account at a SIPC-member firm may be eligible for SIPC protection, though coverage details depend on how the plan and its participant accounts are structured(5) |
| Pros |
|
|
| Cons |
|
|
| Learn more about Roth IRAs | Learn more about 401(k)s |
Roth IRA vs. 401(k): Which one’s better?
Roth IRAs and 401(k)s have different benefits and drawbacks, and one is offered through an employer while the other is opened individually. So, you’ll have to consider certain factors to determine which is better for you.
When to consider a Roth IRA
A Roth IRA is a good option if you:
- Want more investment control. Depending on the IRA custodian, invest in anything from stocks and bonds to ETFs, mutual funds and alternative assets like cryptocurrency.
- Prefer tax-free distributions in retirement. Because you contribute after-tax money, qualified distributions are tax-free. This may be a good option if you think you’ll be in a higher tax bracket when you retire.
- Don’t want RMDs. Unlike traditional IRAs and traditional 401(k)s, Roth IRAs have no RMDs. Mandatory withdrawals are only required after the death of the account owner.(4)
- Want access to your contributions. Withdraw your Roth IRA contributions at any time tax- and penalty-free.
When to consider a 401(k)
A 401(k) is a good option if you:
- Have an employer who will match your contributions. Matching contributions is essentially free money you shouldn’t leave on the table.
- Prefer mutual funds. Mutual funds are the primary investment options for most 401(k)s.
- Want to reduce your taxable income. 401(k) contributions are made using pre-tax dollars, and every dollar you save will reduce your taxable income by an equal amount.
Our picks for 401(k) search and rollover services
- Free 401(k) search and rollover process
- Find your old 401(k) with Capitalize’s proprietary technology
- Guided rollovers to an IRA of your choice
- Find all your old 401(k)s and their hidden fees
- Borrow from your Beagle 401(k) or IRA with 0% net interest
- Robo-advisor available if you roll over your 401(k) to Beagle
The similarities between a Roth IRA and a 401(k)
Roth IRAs and 401(k)s don’t have much in common other than allowing you to grow your retirement savings tax-free. Investment options are different, contribution amounts are different and individuals open IRAs while 401(k)s are employer-sponsored.
Roth IRA vs. 401(k): Where to open these accounts
Open a Roth IRA through banks or traditional brokerages, including Fidelity and Charles Schwab, or with stock trading apps like Robinhood and SoFi Invest®.
401(k)s are only available through an employer.
Alternatives to a Roth IRA and a 401(k)
While Roth IRAs and 401(k)s are great options to help you save for retirement, keep in mind that there are other ways to save:
- High-interest savings accounts. Consider a high-yield savings account if you want easy access to cash savings for an emergency fund or other short-term savings goal.
- Health savings accounts (HSAs). An HSA is a tax-advantaged savings account that can help you pay for healthcare expenses. Using an HSA, you can put money away and withdraw it tax-free when you need it for qualified medical expenses. At age 65, you can take penalty-free distributions from the HSA for any reason. However, you still need to use your money for medical expenses to avoid taxes.
Compare brokerages that offer IRA accounts
Narrow down top brokers by annual fee, stock trade fee and more to find the best for your budget and financial goals.
What is the Finder Score?
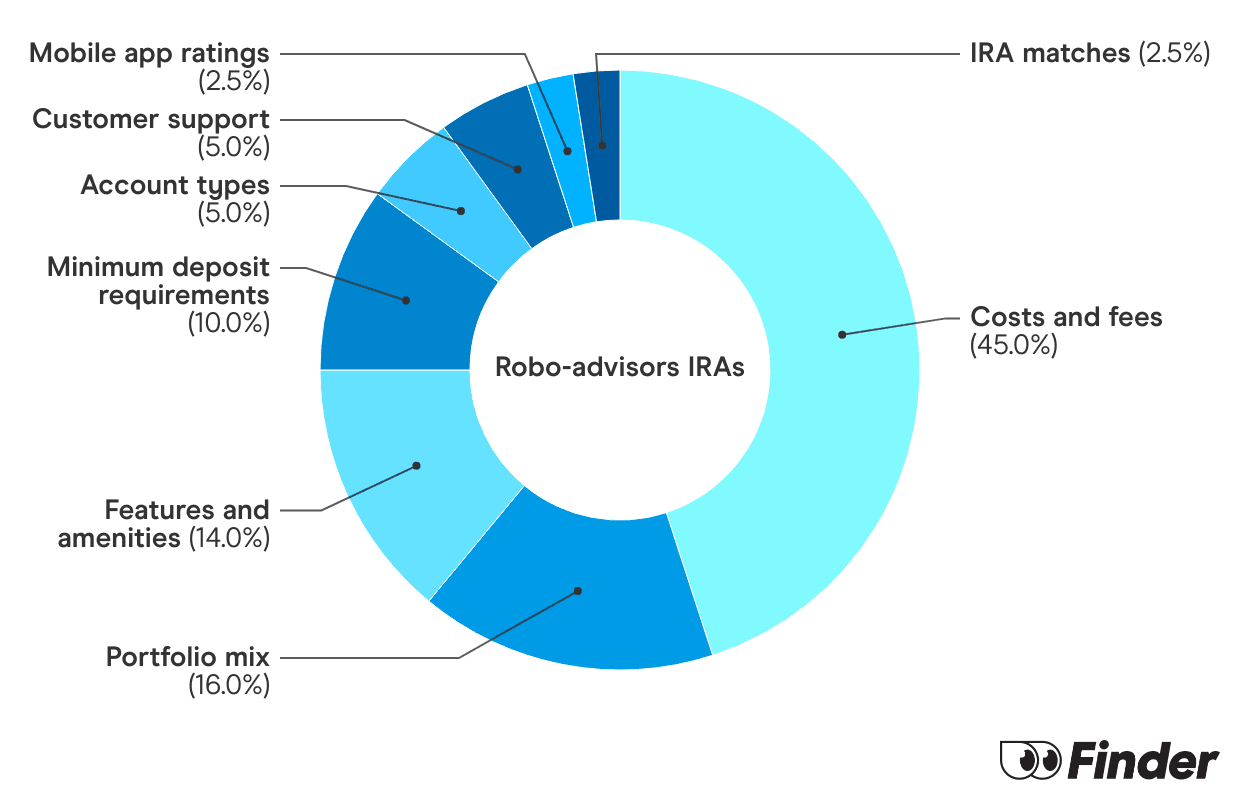
The Finder Score crunches 147 key metrics we collected directly from 18+ brokers and assessed each provider’s performance based on nine different categories, weighing each metric based on the expertise and insights of Finder’s investment experts. We then scored and ranked each provider to determine the best brokerage accounts.
We update our best picks as products change, disappear or emerge in the market. We also regularly review and revise our selections to ensure our best provider lists reflect the most competitive available.
Paid non-client promotion. Finder does not invest money with providers on this page. If a brand is a referral partner, we're paid when you click or tap through to, open an account with or provide your contact information to the provider. Partnerships are not a recommendation for you to invest with any one company. Learn more about how we make money.
Finder is not an advisor or brokerage service. Information on this page is for educational purposes only and not a recommendation to invest with any one company, trade specific stocks or fund specific investments. All editorial opinions are our own.
Frequently asked questions
Sources
Ask a question
More guides on Finder
-
5 Best Roth IRA Investments [With Insights From CFPs]
The best Roth IRA investments may include a mix of index funds, dividend stocks, bond funds and other long-term investments.
-
5 Best SEP IRA Providers of September 2026
Explore the pros and cons of the best SEP IRAs and learn how to open one of these accounts.
-
How to Open a Roth IRA
Here’s what you need to know about opening a Roth IRA in 2024.
-
403(B) vs. Roth IRA: How Do They Compare?
Compare the key differences in contribution limits, tax advantages and investment options between 403(b)s and Roth IRAs.
-
Brokerage Account vs. Roth IRA: How Do They Compare?
Compare the key differences in investment options, contribution limits and tax advantages between brokerage accounts and Roth IRAs.
-
Best Roth IRA Accounts for 2026 — Compare Fees, Features and IRA Matches Across 18 Providers
See Finder’s picks for the best Roth IRA accounts of 2026, compared across fees, features and IRA matches.
-
Best IRA Accounts for 2026 — Compare Fees, Features and IRA Matches Across 18 Providers
See Finder’s picks for the best IRA accounts of 2026, compared across fees, features and IRA matches.
-
Roth IRA vs. Traditional IRA: What’s the Difference?
Learn the differences between a Roth IRA and a traditional IRA.
-
What Is a Roth IRA and How to Open One
Learn how Roth IRAs work and who qualifies to open one.