Finder makes money from featured partners, but editorial opinions are our own.

What is blockchain technology?

How blockchain works, who's using it and why it's much more than just bitcoin.
Key takeaways

  • Blockchain stores records across a network rather than relying solely on one central database.
  • Network rules determine how transactions are verified and added.
  • Applications include cryptocurrency, stablecoin transfers and smart contracts.
  • Blockchain has trade-offs involving cost, speed, privacy and governance.

Blockchain is a type of distributed digital ledger that records information in linked blocks. Cryptographic techniques and network rules help protect these records from unauthorized changes. While bitcoin (BTC) is a cryptocurrency that uses blockchain technology to record transactions, blockchains can also support other digital assets, smart contracts and applications.

Disclaimer: This page is not financial advice or an endorsement of digital assets, providers or services. Digital assets are volatile and risky, and past performance is no guarantee of future results. Potential regulations or policies can affect their availability and services provided. Talk with a financial professional before making a decision. Finder or the author may own cryptocurrency discussed on this page.

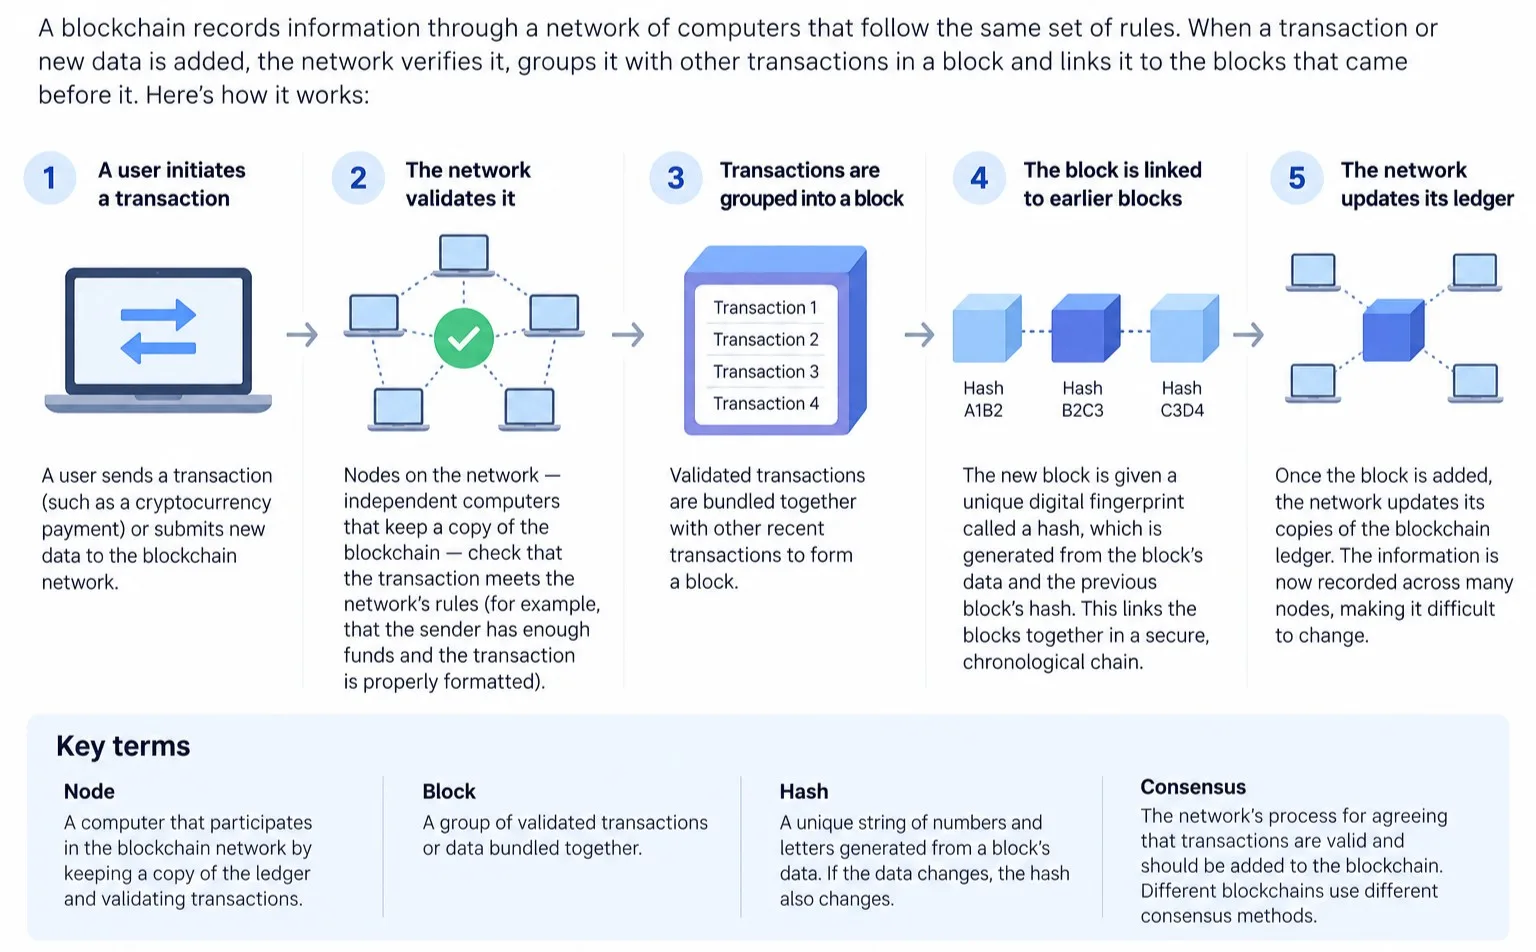
How does blockchain work?

Flowchart on how the blockchain works.

What is blockchain used for?

Blockchain technology supports a range of applications, from cryptocurrency transactions to financial services and supply chain tracking. It allows networks to maintain shared records and, in some cases, execute transactions automatically through smart contracts.

ApplicationWhat blockchain enables
CryptocurrencyRecords transactions involving digital currencies, such as bitcoin, on a shared ledger.
StablecoinsRecords transfers of tokens designed to maintain a stable value, often by tracking a reference currency such as the US dollar.
Decentralized finance (DeFi)Supports financial applications, such as lending and trading, that use smart contracts to execute predefined rules.
Tokenized assetsRecords transfers of digital tokens representing assets or rights, such as securities, real estate interests or commodities.
Supply chainsCreates a shared record of product movements and related data across suppliers, manufacturers and distributors.

Blockchain is not necessary for every application. A blockchain record alone does not prove that a physical product is genuine or that information entered into the system is accurate. Its usefulness depends on how the network is designed, who maintains it and whether participants need a shared record.

What are the different types of blockchain?

Blockchains can be categorized by who can access the network, who can participate in validating transactions and who controls its rules. The three common types are public, private and consortium blockchains.

TypeHow it worksCommon uses
Public blockchainAnyone can generally view the ledger and, depending on the network, submit transactions or help validate them.Cryptocurrencies, decentralized finance and public smart-contract applications.
Private blockchainA single organization controls access and determines who can participate in the network.Internal business records, auditing and data sharing within an organization.
Consortium blockchainA group of selected organizations jointly operates or governs the network.Supply chain management, interbank transactions and shared industry records.

Blockchains can also be described as permissionless or permissioned, depending on the access rules.

  • Permissionless: Participants can generally join the network without approval from a central authority. Public blockchains such as Bitcoin commonly use this model.
  • Permissioned: Access to certain activities, such as submitting transactions or validating blocks, is restricted to approved participants.

These classifications can overlap. For example, a consortium blockchain is typically permissioned, while a public blockchain can restrict certain functions even if anyone can view its records. The appropriate design depends on the level of transparency, control and participation an application requires.

What are the advantages and disadvantages of blockchain?

Blockchain offers a way to maintain shared digital records without necessarily relying on a single central authority. However, its security, cost and performance depend on how the network is designed and operated.

AdvantagesDisadvantages
Shared, auditable records. Participants can verify transactions and track ledger changes.Network fees and variable speeds. Transaction costs and processing times can fluctuate depending on network demand and design.
Tamper resistance. Cryptographic links and network validation make unauthorized changes difficult to carry out without detection.Difficulties correcting errors. Incorrect records can be difficult to amend, particularly on blockchains designed to make transactions effectively irreversible.
Reduced reliance on a single intermediary. Participants can share records without depending entirely on one organization to maintain them.Privacy challenges. Public transaction records can expose information about activity, even when users’ real-world identities are not directly displayed.
Smart-contract automation. Programs can execute predefined actions when specified conditions are met.Software vulnerabilities. Bugs in smart contracts or connected applications can lead to financial losses or other unintended outcomes.
Easier reconciliation. A shared ledger can reduce the need for organizations to maintain and reconcile separate transaction records.Governance and adoption challenges. Participants may disagree about changes, and integrating blockchain with existing systems can be complex and expensive.

What is the blockchain trilemma?

The blockchain trilemma is the idea that blockchain networks face trade-offs between three goals: decentralization, security and scalability.

  • Decentralization: Distributing control across multiple participants rather than concentrating it in one authority.
  • Security: Protecting the network and its records against attacks and unauthorized changes.
  • Scalability: Processing increasing numbers of transactions efficiently.

A blockchain may prioritize some of these goals at the expense of others. For example, a network may improve transaction throughput through design changes that introduce different security or decentralization trade-offs. The trilemma is a useful way to understand these competing priorities, rather than a universal rule that every blockchain can optimize only two of the three.

When does blockchain make sense?

Blockchain is most useful when multiple parties need to maintain and verify a shared record but do not want to rely entirely on one organization to control it. It can help participants coordinate transactions, track changes and automate processes using common rules.

For example, a group of suppliers and distributors could use a shared blockchain ledger to record product movements without relying on one company to maintain the only authoritative record. Similarly, financial applications can use blockchain-based smart contracts to execute transactions when predefined conditions are met.

However, blockchain is not always the best solution. A conventional database may be more suitable when one trusted organization manages the information, needs to correct records frequently or prioritizes fast processing and low operating costs.

Blockchain may make sense when…A conventional database may be better when…
Multiple independent parties need access to a shared record.One organization controls the data and is trusted by other participants.
Participants want to verify records without relying entirely on a central administrator.A central administrator can manage access and maintain the records efficiently.
Transactions need to be traceable and resistant to unauthorized changes.Records need frequent updates, corrections or deletions.
Smart contracts can automate processes between participants.A conventional application can perform the same tasks more simply and cheaply.

Blockchain is worth considering when shared control, verifiable records or decentralized transaction processing provide a meaningful advantage. If a conventional database can meet the same requirements more efficiently, blockchain may add unnecessary cost and complexity.

What is the difference between blockchain and bitcoin?

Blockchain is a technology for recording and verifying information across a network, while bitcoin (BTC) is a digital currency that uses a blockchain to record transactions. Bitcoin is one application of blockchain technology, but the technology can support many other cryptocurrencies, smart contracts and digital applications.

The key differences are:

  • Blockchain is the underlying technology that stores records in linked blocks and uses network rules to validate updates.
  • Bitcoin is a cryptocurrency that operates on its own blockchain, allowing users to transfer value without relying on a central bank or payment processor.
  • Other blockchain networks, such as Ethereum (ETH), support other cryptocurrencies, smart contracts and decentralized applications, including financial services and tokenized assets.

In short, bitcoin uses blockchain technology, but not every blockchain is used for bitcoin or even for cryptocurrency.

Compare crypto exchanges

5 of 17 results
Finder Score Fiat currencies Cryptocurrencies Deposit methods Disclaimer
50
1086
Cryptocurrency, PayPal, P2P
Not available for US citizens
Go to site

Capital at risk

More info
Compare product selection
73
281
Bank transfer, Credit card, Cryptocurrency, Debit card, P2P
Disclaimer: Highly volatile investment product. Your capital is at risk. Not available for US citizens
Go to site

Capital at risk

More info
Compare product selection
26
105
Bank transfer, Debit card, PayPal, Wire transfer
Crypto Trading is offered via eToro USA LLC (NMLS ID: 1769299). This entity is not a registered broker-dealer or FINRA member and your cryptocurrency holdings are not FDIC or SIPC insured. Investments are subject to market risk, including the possible loss of principal.
Important information
Cryptocurrency is offered by eToro USA LLC (“the MSB”) (NMLS: 1769299) and is not FDIC or SIPC insured. Investing involves risk, and content is provided for educational purposes only, does not imply a recommendation, and is not a guarantee of future performance. [website domain name] is not an affiliate and may be compensated if you access certain products or services offered by the MSB.
Go to site

Capital at risk

More info
Compare product selection
OKX logo
1
181
Bank transfer (ACH), Debit card, Wire transfer, Apple Pay, Google Pay, Plaid
Go to site

Capital at risk

More info
Compare product selection
SoFi logo
1
29
External bank transfer (ACH), Inbound wire transfer, ATM deposit
DIGITAL ASSETS EXCEPT SOFI EARN (SOFIE) ARE NOT FDIC INSURED • ARE NOT BANK GUARANTEED • MAY LOSE VALUE SoFi Crypto is offered by SoFi Bank, N.A. Cryptocurrency and digital assets are not deposits, involve risk and are not insured by FDIC. Please refer to the SoFi Crypto Account Agreement and SoFi Crypto Risk Disclosure for additional terms and conditions.
Important information
DIGITAL ASSETS EXCEPT SOFI EARN (SOFIE) ARE NOT FDIC INSURED • ARE NOT BANK GUARANTEED • MAY LOSE VALUE Digital assets offered through SoFi Crypto are highly speculative, involve significant risk, and may result in the complete loss of value. These assets are not deposits, are not insured by the FDIC or SIPC, are not bank guaranteed, and may lose value. SoFi Crypto is offered by SoFi Bank, N.A., a national bank regulated by the Office of the Comptroller of the Currency. SoFi Bank does not provide investment, tax, or legal advice. Please refer to the SoFi Crypto Account Agreement and SoFi Crypto Risk Disclosure for additional terms and conditions. SoFi Earn (SOFIE) is a separate product from SoFi Crypto. SOFIE is a tokenized deposit representing a deposit liability of SoFi Bank, N.A., Member FDIC. Funds represented by SOFIE are eligible for FDIC insurance up to applicable FDIC rules and limits. SOFIE is not a payment stablecoin. Please refer to the SoFi Bank Tokenized Deposit Account Agreement for additional terms and conditions. Annual percentage yield (APY) is variable and subject to change at any time. Rates are current as of 10/20/26. There is no minimum balance requirement. Fees may reduce earnings. Additional information can be found at https://www.sofi.com/crypto/legal/tokenized-deposit-rate-sheet. Funds represented by SOFIE are insured up to $250,000 per depositor, per insured bank, for each account ownership category pursuant to the FDIC's general deposit insurance rules. For more information visit FDIC.gov.
Go to site

Capital at risk

More info
Compare product selection
loading
Showing 5 of 17 results
Disclaimer: Cryptocurrencies are speculative, complex and involve significant risks – they are highly volatile and sensitive to secondary activity. Performance is unpredictable and past performance is no guarantee of future performance. Consider your own circumstances, and obtain your own advice, before relying on this information. You should also verify the nature of any product or service (including its legal status and relevant regulatory requirements) and consult the relevant Regulators' websites before making any decision. Finder, or the author, may have holdings in the cryptocurrencies discussed.

Frequently asked questions

Matt Miczulski's headshot
To make sure you get accurate and helpful information, this guide has been edited by Matt Miczulski as part of our fact-checking process.
Holly Jennings's headshot
Written by

Deputy Crypto Editor

Holly Jennings is the deputy crypto editor and updates writer at Finder, working with writers across all niches to deliver quality content to readers. She’s edited hundreds of financial articles ranging from credit cards to investments. With empathy at heart, she especially enjoys content that breaks down complex financial situations into easy-to-understand information. Prior to her role at Finder, she collaborated with dozens of small businesses to maximize the reach and impact of their blog posts, website copy and other content. In her spare time, she is an award-winning author for Penguin Random House, writing about virtual reality worlds, magical girls and lasers that go pew-pew. See full bio

Holly's expertise
Holly has written 74 Finder guides across topics including:
  • Cryptocurrency
  • Digital assets
  • Investments
  • Personal Banking
James Edwards's headshot
Co-written by

Editor

James Edwards was the global cryptocurrency editor at Finder. He coordinates a distributed team of journalists to help further Finder's mission of helping people make better financial decisions. He has been using Bitcoin since 2013 and began working in the industry in 2017. He takes pride in boiling down complex topics into language his parents can understand. His expertise has seen him called on to report at events such as TechCrunch Disrupt, CoinDesk Consensus and IBM Think and has coordinated a vast number of high-profile interviews with the industry's brightest minds. He is a regular contributor to Nasdaq, The Street and is frequently called upon for market commentary in Australia and abroad. See full bio

Ask a question

Finder.com provides guides and information on a range of products and services. Because our content is not financial advice, we suggest talking with a professional before you make any decision.

By submitting your comment or question, you agree to our Privacy and Cookies Policy and finder.com Terms of Use.

Questions and responses on finder.com are not provided, paid for or otherwise endorsed by any bank or brand. These banks and brands are not responsible for ensuring that comments are answered or accurate.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

2 Responses

    Peter's avatar
    PeterJuly 19, 2019

    I have two blockchain accounts. The first one was creditied with 1000 USD, the second account was creditied with totally 3000 USD. With the exception of approx. 50,00 UISD Balances of both accounts disappeared. Apparently the amounts were sent to another wallet which is not under my control. A screenshot of my transactions can be made available. Brgds

      fayemanuel's avatarFinder
      fayemanuelJuly 20, 2019Finder

      Hi Peter,

      Thanks for contacting Finder.

      Please note that we are a comparison website and we can not vouch for a company as we do not represent any of the providers on our page. Please contact your digital currency exchange provider to look into this. If you believe that it was a scam, you may report it to the proper authority.

      Kind Regards,
      Faye

More guides on Finder

Go to site