-
Commitment to our readers
18 years
Helping you save money
Reviewed
by experts
Cited by
major publications
Finder maintains full editorial independence to ensure for our readers a fair assessment of the products, brands, and services we write about. That independence helps us maintain our reader's trust, which is what keeps you coming back to our site. We uphold a rigorous editorial process that ensures what we write and publish is fair, accurate, and trustworthy — and not influenced by how we make money.
We're committed to empowering our readers to make sound and often unfamiliar financial decisions.
We break down and digest information information about a topic, product, brand or service to help our readers find what they're looking for — whether that's saving money, getting better rewards or simply learning something new — and cover any questions you might not have even thought of yet. We do this by leading with empathy, leaning on plain and conversational language that speaks directly, without speaking down.
Key takeaways
- Full retirement age (FRA) is when you can claim your full, unreduced Social Security benefit. It’s 67 for anyone born in 1960 or later.
- You can claim as early as 62, but your monthly benefit is permanently cut by 30% if your FRA is 67.
- Waiting past your FRA earns delayed retirement credits worth 8% a year, up to 24% more at age 70.
- If you claim before FRA and keep working, the earnings test can temporarily withhold part of your benefit until you reach FRA.
Your full retirement age (FRA) is the age at which you qualify for 100% of your Social Security retirement benefit. For anyone born in 1960 or later, that age is 67 and claiming earlier permanently reduces your monthly check, while waiting longer increases it.
Knowing your FRA matters: as of December 2025, about 87% of Americans aged 65 and older were receiving Social Security, and the average retired worker collected roughly $2,071 a month in early 2026. For many retirees, Social Security is a cornerstone of their income — so the age you claim can shape your finances for the rest of your life.
What is the full retirement age?
Full retirement age is the age at which you’re entitled to unreduced Social Security benefits. It’s often confused with the earliest age you can claim (62) and with Medicare eligibility (65) but it’s a separate milestone tied to your birth year.
Under the 1983 Social Security amendments, Congress gradually raised the FRA from 65 to 67. Here’s your full retirement age based on when you were born.
| Birth year | Full retirement age |
|---|---|
| 1943–1954 | 66 |
| 1955 | 66 and 2 months |
| 1956 | 66 and 4 months |
| 1957 | 66 and 6 months |
| 1958 | 66 and 8 months |
| 1959 | 66 and 10 months |
| 1960 and later | 67 |
If you were born on January 1, your benefit is calculated as though you were born in the previous year.
How your retirement age affects your Social Security
You can start collecting Social Security at 62, but claiming before your full retirement age permanently reduces your monthly benefit. Here’s how much you’d give up by filing at 62, based on your birth year.
| Birth year | Full retirement age | Benefit reduction if you claim at 62 |
|---|---|---|
| 1943–1954 | 66 | 25% |
| 1955 | 66 and 2 months | 25.83% |
| 1956 | 66 and 4 months | 26.67% |
| 1957 | 66 and 6 months | 27.5% |
| 1958 | 66 and 8 months | 28.33% |
| 1959 | 66 and 10 months | 29.17% |
| 1960 and later | 67 | 30% |
The closer you get to your full retirement age, the smaller the reduction. Here’s how the cut shrinks for someone born in 1960 or later, with a full retirement age of 67.
| Age you claim | Benefit reduction (FRA 67) |
|---|---|
| 62 | 30% |
| 63 | 25% |
| 64 | 20% |
| 65 | 13.33% |
| 66 | 6.67% |
| 67 | 0% |
Social Security calculates the reduction using a two-tier formula: your benefit drops by 5/9 of 1% for each of the first 36 months you claim early, then 5/12 of 1% for every additional month before that.
The Social Security earnings test
If you claim before your full retirement age and keep working, the earnings test can temporarily reduce your benefit. In 2026:
- If you’re under FRA all year: Social Security withholds $1 in benefits for every $2 you earn above $24,480.
- In the year you reach FRA: the rule is gentler: $1 is withheld for every $3 you earn above $65,160, and only earnings before the month you hit FRA count.
- Once you reach FRA: there’s no limit, and your earnings no longer reduce your benefit.
Withheld benefits aren’t lost forever. Once you reach full retirement age, Social Security recalculates your payment to credit back the months benefits were withheld. To estimate the impact, use the SSA’s Retirement Earnings Test Calculator.
What happens if you work past full retirement age?
If you delay claiming past your FRA, you earn delayed retirement credits that boost your benefit by about 8% a year until age 70. There’s no advantage to waiting beyond 70. For someone born in 1960 or later, here’s how the increase adds up.
| Age you claim | Benefit increase (FRA 67) |
|---|---|
| 67 | 0% |
| 68 | 8% |
| 69 | 16% |
| 70 | 24% |
Is it better to claim early or delay?
There’s no universal answer and comes down to: how long you expect to live, whether you need the income now and how a claim affects a spouse. The key concept is your break-even age: the point at which the larger delayed checks catch up to, and overtake, the smaller early ones.
Say your full benefit at 67 is $1,000 a month. Claim at 62 and it’s cut to $700; wait until 70 and it grows to $1,240. By claiming early, you collect eight extra years of checks — a head start of about $67,000 by age 70. But the delayed benefit pays $540 more each month, so it takes roughly 10 years to close that gap. In this example, the break-even lands around age 80 to 81.
The takeaway: if you expect to live past your early 80s, delaying tends to pay more over your lifetime. If you’re in poorer health or need the money sooner, claiming early may make more sense. Delaying also raises the survivor benefit for a lower-earning spouse, which often tips the decision toward waiting for the higher earner in a couple.
How to factor Social Security into retirement planning
Social Security is designed to replace only about 40% of an average earner’s pre-retirement income, so it’s rarely enough on its own. Most people supplement it with other sources, such as an individual retirement account (IRA) or a 401(k). That means your FRA should be just one input in a broader plan.
Other timing factors to weigh include when you can tap your other accounts without penalty, whether you can afford to retire early and personal circumstances that might keep you working longer.
A few key ages to keep in mind:
- 59½: You can take distributions from IRAs, 401(k)s and pension plans without the 10% early withdrawal penalty. Withdrawals from traditional accounts are still subject to income tax — unless the money is in a Roth IRA or Roth 401(k).
- First two years of a SIMPLE IRA: Withdraw early and you may face an extra 25% penalty on top of the usual tax, so it can pay to wait.
- 62 to 70: Your Social Security claiming window, where every month you wait increases your benefit.
How much do Americans think they need to retire?
Expectations vary widely. In a Finder survey of 2,033 US adults, one in five (20%) thought they could retire comfortably on $250,000 or less, while a combined 31% said they’d need more than $1 million.
How much do you think you ll need to have saved to retire comfortably?
| Response | % of Americans |
|---|---|
| Less than $250k | 20% |
| $750k - $999K | 14% |
| $500k - $749k | 16% |
| $5 million + | 4% |
| $4 - $4.99 million | 1% |
| $3 - $3.99 million | 2% |
| $250k - $499k | 19% |
| $2 - $2.99 million | 4.38% |
| $1.5 - $1.99 million | 6.20% |
| $1 - $1.49 million | 14.46% |
Compare retirement accounts
Since Social Security is likely to cover only part of your retirement income, a tax-advantaged account can help fill the gap. Compare IRA and retirement account providers below.
Looking for other options? Check out these similar products.
How we picked theseWhat is the Finder Score?
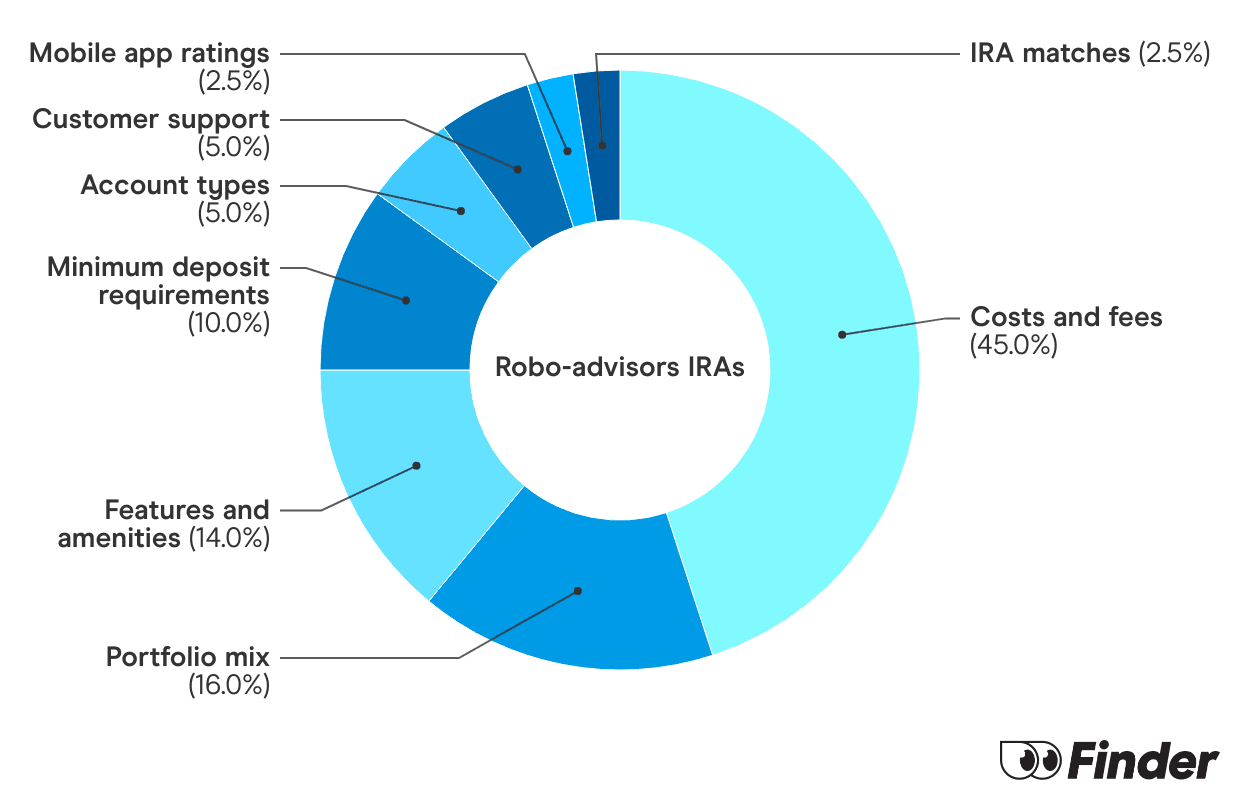
The Finder Score crunches 147 key metrics we collected directly from 18+ brokers and assessed each provider’s performance based on nine different categories, weighing each metric based on the expertise and insights of Finder’s investment experts. We then scored and ranked each provider to determine the best brokerage accounts.
We update our best picks as products change, disappear or emerge in the market. We also regularly review and revise our selections to ensure our best provider lists reflect the most competitive available.
Paid non-client promotion. Finder does not invest money with providers on this page. If a brand is a referral partner, we're paid when you click or tap through to, open an account with or provide your contact information to the provider. Partnerships are not a recommendation for you to invest with any one company. Learn more about how we make money.
Finder is not an advisor or brokerage service. Information on this page is for educational purposes only and not a recommendation to invest with any one company, trade specific stocks or fund specific investments. All editorial opinions are our own.
Bottom line
Your full retirement age is when you’re entitled to your full Social Security benefit — 67 for anyone born in 1960 or later. You can claim as early as 62, but your monthly check will be permanently smaller, and delaying past your FRA raises it up to age 70. Because Social Security is likely only part of your retirement income, it’s worth pairing your claiming decision with other retirement plans to build a fuller picture.
Frequently asked questions
-
Full retirement age (FRA) is the age at which you can claim 100% of your Social Security retirement benefit. It depends on your birth year: it's 66 for people born between 1943 and 1954, rises in two-month steps for those born from 1955 to 1959, and is 67 for anyone born in 1960 or later.
-
Yes. Age 62 is the earliest you can claim Social Security retirement benefits. But claiming before your full retirement age permanently reduces your monthly payment — by 30% if your FRA is 67. The reduction applies for the rest of your life, including future cost-of-living adjustments.
-
Delaying past your full retirement age earns delayed retirement credits worth about 8% a year, up to a maximum of 24% more at age 70 for those with an FRA of 67. There's no benefit to waiting beyond 70, as the credits stop accruing.
-
In 2026, if you're under full retirement age for the whole year, Social Security withholds $1 in benefits for every $2 you earn above $24,480. In the year you reach FRA, the limit rises to $65,160 and only $1 is withheld for every $3 over it. Once you reach FRA, there's no earnings limit.
-
It depends on your health, income needs and life expectancy. Claiming at 62 gives you smaller checks sooner; waiting until 67 (or 70) gives you larger checks later. The break-even age — when the larger delayed benefit overtakes the total from claiming early — typically falls around age 80 to 81. Living past that point generally favors delaying.
-
No. Medicare eligibility starts at 65 regardless of your Social Security full retirement age. Because the FRA is now 67 for most people, many reach Medicare eligibility before they reach their FRA, so it's worth planning for the two milestones separately.
-
Once you reach full retirement age, the earnings test no longer applies, so you can work and earn any amount without reducing your Social Security benefit. If you also delay claiming past your FRA, you'll earn delayed retirement credits that increase your monthly payment until age 70.
-
Yes. The reduction for claiming before full retirement age is permanent and doesn't reverse when you reach FRA. The one exception is benefits withheld under the earnings test, which are credited back through a higher payment once you reach full retirement age.
-
Finder writers are subject matter experts and use primary sources, in-depth research and interviews with other experts to ensure you're getting accurate, up-to-date information. Articles are fact checked in line with our editorial guidelines.
- “Retirement Benefits,” Social Security Administration, 2026
- “Benefits Planner: Retirement Age and Benefit Reduction,” Social Security Administration
- “Delayed Retirement Credits,” Social Security Administration
- “Receiving Benefits While Working,” Social Security Administration
- “What is the average monthly benefit for a retired worker?,” Social Security Administration, January 2026
Kimberly Ellis is a personal finance writer at Finder, specializing in banking and financial literacy. After teaching in public and private schools, Kimberly zeroed in on personal financial education to help families and kids develop lifelong money skills. She hails from New York City, graduating summa cum laude from Queens College with a BA in elementary education and mathematics, as well as a New York State teaching certificate. She’s also an aspiring polyglot, always in a book and forever on the hunt for the perfect classic red lipstick. See full bio
- Kids' banking
- Financial literacy for kids
- K–12 education
More guides on Finder
-
5 Best SEP IRA Providers of September 2026
Explore the pros and cons of the best SEP IRAs and learn how to open one of these accounts.
-
How to Open a Roth IRA
Here’s what you need to know about opening a Roth IRA in 2024.
-
Roth IRA vs. savings account: How do they compare?
Compare the key differences in investment options, contribution limits and tax advantages between Roth IRAs and savings accounts.
-
Brokerage Account vs. Roth IRA: How Do They Compare?
Compare the key differences in investment options, contribution limits and tax advantages between brokerage accounts and Roth IRAs.
-
Roth IRA vs. 401(K): How Do They Compare?
Compare the key differences in investment options, contribution limits and tax advantages between Roth IRAs and 401(k)s.
-
Best Roth IRA Accounts for 2026 — Compare Fees, Features and IRA Matches Across 18 Providers
See Finder’s picks for the best Roth IRA accounts of 2026, compared across fees, features and IRA matches.
-
Best IRA Accounts for 2026 — Compare Fees, Features and IRA Matches Across 18 Providers
See Finder’s picks for the best IRA accounts of 2026, compared across fees, features and IRA matches.
-
Roth IRA vs. Traditional IRA: What’s the Difference?
Learn the differences between a Roth IRA and a traditional IRA.
-
What Is a Roth IRA and How to Open One
Learn how Roth IRAs work and who qualifies to open one.
-
Goldco Review 2026: Pros and Cons
Pros and cons to consider before you sign up for a Goldco precious metals IRA.