Kikoff Credit Building Review


- Fee
- From $5 per month
- Minimum deposit to open
- $0
Our verdict
A few interesting products without much risk, but they may not work in the way you think they do.
Kikoff is a credit-building fintech with multiple products designed to help you build a better credit history. There's a unique line of credit called the Kikoff Tradeline, rent reporting services and more. The tradeline is a very odd product, and you might be better off with another credit-building tactic if you want the ability to borrow money. You also must pay a monthly membership fee of $5, $20 or $35, with the main difference between the plans being the size the of the credit limit that's reported to the bureaus.
Best for: Those who want to build credit history without debt.
Pros
-
Tradeline to build credit history
-
No hard credit checks
-
Rent reporting
-
Good customer ratings
-
Dispute and budgeting tools
Cons
-
Tradeline doesn't come with a card
-
No longer offers secured card
-
Can't avoid a monthly fee
Who is Kikoff best for?
Kikoff is best for someone looking to start building their credit history or those who need to rebuild a poor credit history. Kikoff offers different types of credit-building products, including a unique line of credit it calls a tradeline, rent reporting services and a dispute tool.
However, the “line of credit” isn’t like a regular line of credit, in that you don’t get a card and it’s only used to pay for your monthly membership fee for Kikoff. So if you were looking for a secured credit card, or a way to borrow money for outside purchases, this isn’t the product for you.
But on the other hand, if you were looking for a way to build credit history in a way that doesn’t give you the temptation to max out a credit card or take on debt, then this might be the way to go.
Kikoff plans
The main difference between the plans is your tradeline amount, and a few extra services.
| Plan | Cost | Details |
|---|---|---|
| Basic | $5/month |
|
| Premium | $20/month | Features of Basic, plus:
|
| Ultimate | $35/month | Features of Basic and Premium, plus:
|
What we like about Kikoff
Kikoff offers multiple ways to improve your credit history, while avoiding hard credit pulls. Kikoff will report your accounts each month, but which credit bureau it reports to depends on the Kikoff product you choose.
Other products and services address the major factors of your FICO 8 Score, which are payment history, credit utilization, length of credit history and credit mix. To sign up for any of their products, you’ll need to create a free Kikoff account with an email and password, and you’ll need a bank account to pay for credit-building loans or repay the tradeline.
Kikoff tradeline
This is the core Kikoff service that’s offered with every plan.
The Kikoff tradeline is a used to finance your monthly Kikoff plan and is designed to build credit history. The tradeline amount reported depends on your plan ($750, $2,500 or $3,500). There’s no interest charges, credit check, annual fees or late fees.
Now to the meat of how this service actually works.
First, you select a monthly plan. Then, using the tradeline, you finance the cost of your plan with your Kikoff tradeline and repay Kikoff each month with your debit card. In other words, the tradeline is covering your Kikoff monthly plan costs, and those payments are reported to the credit bureaus, and you repay the amount the tradeline paid with a linked debit card. The payments are reported to the three major credit bureaus; Equifax, Experian and TransUnion.
Kikoff tradeline can not be used outside of Kikoff. You don’t get a debit or credit card for spending, and you can’t use the tradeline to fund anything else.
Get your rent payments reported
Kikoff can report your rent payments to Equifax and TransUnion, and only on-time payments will be reported. Rent reporting is included with every Kikoff plan, starting with Basic at $5 per month. For an additional one-time fee of $50, Kikoff will report rent payments retroactively for up to 24 months.
To get rent payments reported, you must link the bank account you’re using to pay your rent and send in a lease or landlord agreement for verification so Kikoff can send verifiable payments to Equifax and TransUnion.
Credit monitoring and disputes
Every Kikoff plan includes a weekly credit report, and Premium and Ultimate add 3-bureau credit reports and scores. Kikoff also has an AI credit dispute tool that helps you flag errors on your Equifax credit report and drafts a dispute letter you can review before it’s sent. You can mail disputes yourself for free, or on Premium and Ultimate, Kikoff will handle the postage and paperwork for you.
Debt negotiation
Premium and Ultimate members can use Kikoff’s debt negotiation tool for eligible debts like collections and charge-offs. With your permission, Kikoff contacts the collector to request a settlement offer, and you can choose to accept or decline it.
What could be better
Keep in mind that to use most of Kikoff’s credit-building tools or products, you’ll need a paid monthly membership, ranging from $5 per month to $35 per month. On top of that, not all of Kikoff’s products report to all three major bureaus. Rent reporting only goes to Equifax and TransUnion, and bill reporting only goes to TransUnion.
Kikoff’s dispute tool only works with your Equifax credit report. And also, know that disputing and removing errors from your credit report is something you can do on your own for free by contacting any of the major bureaus.
Hot tip: Bye-bye secured card
Tradeline isn’t that useful
Even though it doesn’t have any fees or interest, the Kikoff tradeline can’t be used for purchases outside of Kikoff, and it doesn’t come with a physical card. This credit is only designed for credit-building, and is used to “fund” your chosen monthly plan.
It’s a tough sell. And unlike credit-building loans that return your payments to you, the Kikoff tradeline doesn’t return any funds to you. You do not get money back after, and it’s not a loan, and you don’t get a card for spending.
Compare Kikoff to other credit-building products
Narrow down top credit-building services by fees, APR and features. For a better comparison, tick the Compare box next to multiple providers to view them side by side.
What is the Finder Score?
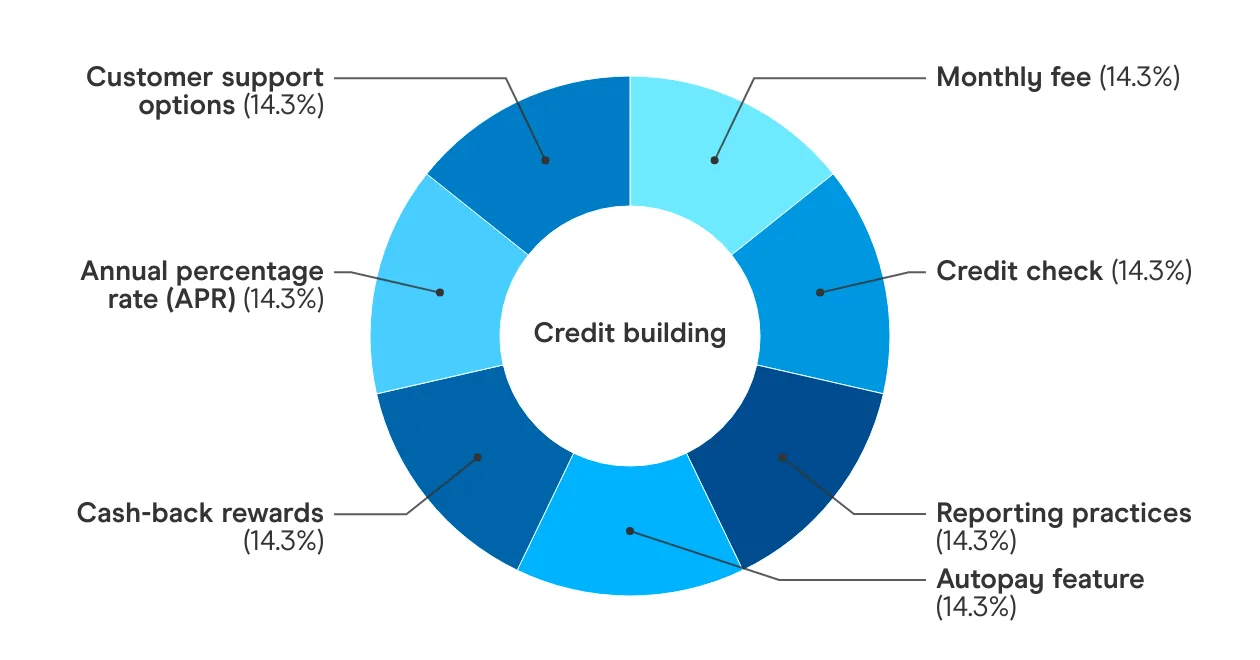
The Finder Score crunches over 30 credit-building cards and products from dozens of financial institutions and fintech companies. It takes into account the product's monthly fees, reporting practices, eligibility requirements, rewards programs, APR and features — this gives you a simple score out of 10. To provide a Score, Finder’s banking experts only consider credit-building cards that report to the major credit bureaus as “credit-building cards.” If a card that claims it can build credit does not have any reporting practices, it is not considered a credit-building card and isn’t scored.
Kikoff customer reviews and ratings
| BBB accredited | Yes |
|---|---|
| BBB rating | A+ |
| BBB customer reviews | 4.35 out of 5 stars, based on 927 customer reviews |
| Trustpilot score | 3.9 out of 5 stars, based on 2,345 customer reviews |
| Customer reviews verified as of | 23 October 2026 |
Kikoff’s customer feedback is pretty good.
The majority of customer reviews on Trustpilot and the Better Business Bureau (BBB) is positive, with customers often stating they were skeptical of the fintech at first but then were surprised about the results and the improvements they saw to their credit. Others point out that it’s an easy and cost-effective way to build credit history, has an easy-to-navigate app and the customer phone line is helpful.
Complaints on its Better Business Bureau (BBB) page are mostly from customers who didn’t know how the credit account (now called tradeline) worked, and saying they didn’t know it doesn’t come with a physical card. Once customers figured that out, they canceled the account only to find out that canceling it can cause damage to their credit. Kikoff has responded to these complaints, explaining the product and apologizing for the confusion. They’ve also made attempts at resolving grievances.
On Reddit, most of the threads are users asking if Kikoff is legitimate, and the response is varied. Many of the threads say that Kikoff is a good supplement to other credit-building methods, and it’s an inexpensive way to start rebuilding credit history. Others tell stories about their credit increasing dramatically over a few months, and some users simply recommend traditional credit cards instead if they can qualify.
Credit building card ratings
★★★★★ — Excellent
★★★★★ — Good
★★★★★ — Average
★★★★★ — Subpar
★★★★★ — Poor
Read the full methodology of how we rate credit building cards.
Frequently asked questions
Your reviews
Bethany Finder
Banking editor
You are about to post a question on finder.com:
- Do not enter personal information (eg. surname, phone number, bank details) as your question will be made public
- finder.com is a financial comparison and information service, not a bank or product provider
- We cannot provide you with personal advice or recommendations
- Your answer might already be waiting – check previous questions below to see if yours has already been asked
Finder only provides general advice and factual information, so consider your own circumstances, or seek advice before you decide to act on our content. By submitting a question, you're accepting our finder.com Terms of Use and Privacy and Cookies Policy.
This site is protected by reCAPTCHA and the Privacy Policy and Terms of Service apply.