Credit Cards for Bad Credit & Alternatives

Where to find credit cards for bad credit in Canada, plus a few alternatives worth checking out.

Hand holding credit card and tapping at a POS

Have a low credit score? It’s possible to access credit. You can qualify for a few credit cards or no-interest cash advances. Explore your options here.

Credit cards for bad credit in Canada and alternatives

ProviderHow much you can borrowInterest rateDeposit required?
Neo Secured MastercardUp to $10,00019.99%–29.99% (up to 25.24% in Quebec)Yes, $50 – $10,000Go to site
Capital One Guaranteed Secured MastercardUp to $2,50029.9% (21.9% in Quebec)Yes, $75 – $2,500
Home Trust Secured VisaUp to $10,00019.99% ($0 annual fee) or 14.9% ($59 annual fee)Yes, $500 – $10,000
Nyble Credit LineUp to $2500%NoGo to site
KOHO Cover Cash AdvanceUp to $5000% + monthly fee from $2No
Go to site
Bree Cash AdvanceUp to $7500%NoGo to site

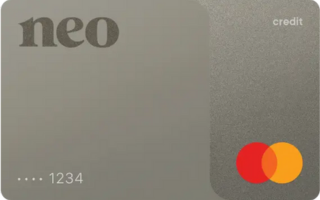
Neo Mastercard

Neo Secured Mastercard

Pros

  • Flexible criteria. Low credit score? Inconsistent income? You're welcome to apply.
  • Instant decision. Apply online and find out if you're approved straight away.
  • Rebuild credit. Give your credit score a boost by making on-time payments.

Cons

  • Monthly fee. You'll need a Build membership to get this card, which is Neo's name for its level 2 membership, costing $9.99 per month. Other secured cards offer no-fee options.
  • Deposit required. You'll need at least $50 to qualify.
  • High rates for bad credit. Expect an interest rate at the top end of this card's rate range.

Is it easy to get approved?

Getting approved is straightforward because there are no credit score or income requirements. You can complete a quick online pre-qualification check without affecting your credit score, and you set your credit limit by providing a refundable security deposit.

Go to site

Any rewards or perks?

Earn cash back when you shop at 10,000+ Neo partners, including well-known brands like Walmart, Amazon, Netflix, Disney+, Gap, Old Navy and Second Cup.

Is it legit?

100%. Neo Financial is a Canadian fintech based in Calgary. It’s registered as a Money Services Business with FINTRAC. Neo issues the Secured Neo Mastercard under a licence from Mastercard International.

Neo Secured Mastercard review
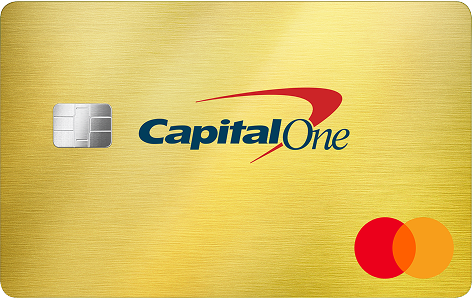
Capital One Mastercard

Capital One Secured Mastercard

Pros

  • No fees. No need to worry about membership requirements or yearly fees. Keep more money in your pocket.
  • Improve your credit score. Staying within your credit limit and making on-time payments could help you build or rebuild your credit.
  • Fast online pre-approval. Find out if you qualify without your credit score taking a hit.

Cons

  • Deposit required. Have $75 – $2,500 ready.
  • Low maximum. The maximum credit limit for this card is $2,500 (vs. $10,000 for other secured cards).
  • Interest rate of 29.9% (21.9% in Quebec). This is at the highest end of the range.
  • No cash back. Unlike the Neo secured card, you don't earn cash back.

Is it easy to get approved?

Capital One offers “guaranteed” approval. That doesn’t actually mean approval is a sure thing. You won’t qualify if…

  • You’re prohibited from accessing credit for legal reasons.
  • You have a frozen credit profile.
  • You already have a Capital One account.
  • You have an account in bad standing over the last year.
  • You don’t have a deposit.

Any rewards or perks?

You can’t earn exciting rewards like cash back with this card, but it does come with some boring but useful insurance coverage. Policies include purchase assurance, extended warranty cover, car rental insurance, travel accident insurance and baggage delay insurance.

Is it legit?

Yes. Capital One Canada is a division of Capital One Bank, which in turn is a subsidiary of Capital One Financial Corporation in the USA. The corporation is a FORTUNE 500 company and is listed on the New York Stock Exchange. Capital One’s Canadian HQ is in Toronto.

Capital One credit cards

Home Trust Secured Visa

Home Trust Secured Visa

Pros

  • $0 annual fee option. Save your money by choosing the no-fee card.
  • Decent rate for a secured card. Get a 19.99% standard rate.
  • Option for a better rate. You can get a 14.9% rate if you pay a $59 annual fee.
  • Build credit. Responsible spending and on-time payments can help you start your journey back to good credit.

Cons

  • Security deposit required. You'll need to shell out at least $500, which is much higher than the other secured cards.
  • Not available in Quebec. Consider other options if you're a Quebec resident.
  • No cash back. If you want to be rewarded for your spending, this isn't the card for you.

Home Trust Secured Visa review

Is it easy to get approved?

The Home Trust Secured Visa is designed for people with unconventional credit histories. So if you have bad credit, you’re a newcomer to Canada or you’re a student with limited credit, there’s a chance to be approved. But you must provide a security deposit, and you cannot be in bankruptcy.

Any rewards or perks?

No. This no-frills card does exactly what it says on the label, so don’t expect any flashy rewards or extras.

Is it legit?

It’s absolutely legit. Home Trust was founded in 1977 and is headquartered in Toronto. It merged with Fairstone Bank in 2025 to create Canada’s largest alternative lender. Home Trust is also a member of the Canada Deposit Insurance Corporation (CDIC).

Secured credit cards are not your only option

Secured credit cards are a reliable way to access credit if your credit score isn’t the best, but if you’re looking for alternatives, cash advance providers are around. They charge 0% interest, don’t check credit and don’t require a deposit.

The downside? You can only borrow up to $750, and you don’t get a card you can tap at checkout.

Nyble

Nyble credit line

Pros

  • No credit check. You don't need to pass a credit check to qualify, which helps if you have bad credit.
  • No interest or mandatory fees. Unlike a credit card, Nyble's interest is 0%, which is much better than 19.99 - 29.99%. And if you pick standard delivery, the fee is also $0.
  • Build credit. Just like a bad credit credit card, you can use Nyble to build your credit history. Not all cash advance apps offer this perk.
  • Flexible repayments. Nyble offers the flexibility to change the payment date without late fees, so you've got wiggle room if you're hit with an unexpected bill.

Cons

  • Small amount. You can only borrow up to $250.
  • Slow funding. If you want funding without paying a fee, you'll need to wait one to three business days to get your money.
  • Limited borrowing. Nyble doesn't give you a continuous balance to draw from. You can't borrow more if you have an active advance, even if you're below your approved limit. You have to pay off the existing loan first.

Is it easy to get approved?

Nyble’s eligibility requirements are much more flexible than standard credit cards. It doesn’t do credit checks, so bad credit won’t stop you from getting a loan. It has a few basic requirements: you need a direct deposit income of at least $1,000/month, and you can’t have any existing Nyble accounts that are not in good standing.

Go to site

Any rewards or perks?

With a free account, you get access to your Equifax credit score and you can earn reward points for on-time payments. Redeem points for gift cards to popular retailers. Upgrade to an $11.99/month premium membership to get instant funding, credit monitoring, balance protection insurance, identity theft coverage and a boosted rewards earn rate.

Is it legit?

Nyble is completely legit. This Toronto-based platform launched in 2022 and is run by Canadian fintech Fincentify Inc. Nyble also has an average rating of 4.8/5 from 8,000+ Trustpilot reviews.

Nyble review

KOHO logo

KOHO Cover

Pros

  • No credit check. Like other cash advance providers, KOHO skips the credit check.
  • Repayment flexibility. Repay your cash advance any time without late penalties.
  • No interest. KOHO charges zero interest, but it does charge a monthly fee.

Cons

  • Monthly fee for the cash advance. The fee starts at $2.
  • KOHO account required. It's free if you have direct deposit set up or if you add $1,000 per month. (Otherwise, there's a monthly account fee.)
  • Won't build credit. KOHO doesn't report cash advance payments to the credit bureaus, so you'll need to look for other ways to boost your credit score, such as Nyble or secured credit cards.

Is it easy to get approved?

In addition to skipping the credit check, KOHO doesn’t require any proof of income, which other cash advance providers do ask for. KOHO also doesn’t require a security deposit.

Cash Advance Apps
ENDS SOON
Get $75 from Finder
Become a Finder member, then open and fund a new KOHO account through Finder as a first-time customer. Keep the account open until February 15, 2027. Offer ends December 30, 2026. Separate T&Cs apply.
SIGN UP & GET $75

Any rewards or perks?

KOHO Cover subscribers get access to a free credit report, financial coaching and priority support. Your KOHO account also gets other benefits, including instant e-Transfers, cash back on spending and up to 3.5% interest on your savings balance. Higher-tier accounts enjoy zero foreign transaction fees.

Is it legit?

We can confirm that KOHO Cover is perfectly legit. KOHO is a Toronto-based fintech that has been in business since 2014. It is also in the process of acquiring a Schedule 1 banking licence.

KOHO Cover review

Bree

Bree cash advance

Pros

  • No credit check. You can qualify with bad credit.
  • Offers 0% interest, $0 fees. Only repay the money you borrow, nothing more, which is good news no matter your credit score. Pay no fees if you pick standard delivery, which takes one to three business days.
  • Borrow up to $750. This is higher than other cash advance apps.

Cons

  • Won't improve your credit score. A Nyble cash advance or secured credit card can help you build credit, but a cash advance from Bree won't.
  • Instant transfer fee. Need cash fast? You'll have to pay a fee of $2.99 – $45.99 to get it within minutes.
  • Slow funding. If you want a fee-free cash advance, it could take one to three business days for the funds to land in your account.

Is it easy to get approved?

Unlike a traditional loan or credit card, you don’t need to jump through a whole lot of hoops to get a Bree cash advance. You’ll need a consistent source of income to qualify for funding, and Bree accepts a variety of income types, including government benefits. Bree will also check whether you will have enough money in your account after paying back your advance to cover your regular expenses.

Go to site

Any rewards or perks?

Sort of. You also get access to a free budgeting tool to help you track your income and expenses, plus a weekly newsletter with money management tips. They’re not the most exciting perks, but they could come in handy.

Is it legit?

Bree is 100% legit. This Toronto-based fintech has received thousands of positive customer reviews on Trustpilot.

Bree review

What are the best credit cards for bad credit in Canada?

If we’re basing this on how easy it is to access credit, the best credit cards for bad credit in Canada actually aren’t even credit cards; they’re cash advance apps. Cash advance apps don’t do credit checks, don’t require a security deposit and accept many types of income. They also don’t charge interest.

Among the credit cards, Neo offers the best perks, but you’ll be dinged with $9.99 per month.

If you want to avoid annual fees and don’t expect to pay off your balance every month, Home Trust Visa has a lower rate (19.99%) than Capital One’s 29.9% (21.9% in Quebec). However, it requires at least $500 for the security deposit.

What are the best unsecured credit cards for bad credit?

The only unsecured credit card for bad credit we’ve seen in Canada is Fidem Finance’s Fidem Mastercard. It doesn’t require a security deposit and offers a credit limit of up to $3,000. However, a monthly fee starting at $10 applies.

Is the Fidem Mastercard legitimate?

The Fidem Mastercard is issued by Peoples Trust Company, which is federally regulated by the Office of the Superintendent of Financial Institutions (OSFI).

Credit cards vs. cash advance apps for bad credit

Should you choose a credit card or a cash advance app? The reality is that both options have their pros and cons.

The strength of credit cards is in their convenience. The money is there whenever you need it, and you can just tap and pay in seconds. And if you use your card responsibly, it can help you rebuild credit.

The weakness of credit cards is the cost. Interest rates of up to 29.99% apply, and you also need to come up with a security deposit just to get a bad credit credit card in the first place.

Cash advance apps can’t match the convenience of credit cards. You need to request an advance whenever you need money, loan amounts are lower, and you can’t borrow more until you pay off your last loan.

But affordability is the biggest strength of a cash advance app. Cash advance apps Bree and Nyble charge no interest or mandatory fees, making their advances a whole lot easier to repay.

What about prepaid cards?

A prepaid card lets you buy stuff in store and online just like a regular credit card. But instead of spending borrowed money, you pay with your own money that you load onto the card.

It’s not a good fit for everyone. On the plus side, it’s easy to get a prepaid card even if you have bad credit, and you don’t need to worry about taking on debt. These cards also make it easy to stick to a budget while avoiding overdraft fees from accidental overspending.

The catch is that you need to have money to load onto the card in the first place. So if you’re here because you need to borrow money with a credit card, a prepaid card is basically useless.

The other downside is that unlike a regular credit card, a prepaid card won’t help build your credit history.

Prepaid credit cards in Canada

Are there other ways to get money with bad credit?

  • Authorized credit card user. You could get your partner or a family member to add you as an authorized user on their credit card account. You will get a card you can use to make purchases, helping to build your credit history.
  • Personal loans. Poor credit might stop you getting a loan from a bank, but there are plenty of alternative lenders that offer bad credit personal loans. Approval is based on your income rather than your credit score, but high interest rates apply. Learn more about the best bad credit loans.
  • Line of credit. Some online lenders also offer lines of credit for bad credit. This gives you flexible access to funds when you need them, but high interest rates and fees apply.
  • Side hustles. Instead of taking on more debt, why not look for ways to make more money instead? From online surveys and get-paid-to (GPT) apps to freelancing, pet sitting and delivering food, there are lots of different ways you can earn some extra income. Find some inspo in our guide to side hustles in Canada.

Bottom line

Bad credit isn’t all bad news. You can still access credit with a secured credit card or a cash advance app, and some of these options will also help you rebuild your credit. Compare credit cards for bad credit as well as cash advance alternatives to get the funding you need.

Frequently asked questions

Leanne Escobal's headshot
To make sure you get accurate and helpful information, this guide has been edited by Leanne Escobal as part of our fact-checking process.
Tim Falk's headshot

Tim Falk is a freelance writer for Finder. Over the course of his 20-year writing career, he has reported on a wide range of personal finance topics. Whether you're investing in stocks and ETFs, comparing savings accounts or choosing a credit card, Tim wants to make it easier for you to understand. When he’s not staring at his computer, you can usually find him exploring the great outdoors. See full bio

Tim's expertise
Tim has written 597 Finder guides across topics including:
  • Banking
  • Personal Loans
  • Car Loans
  • Stock Trading
  • Cryptocurrency

More guides on Finder

Go to site