6 Secured Credit Cards & Alternatives

Learn where to find secured credit cards in Canada, and compare alternative funding options for no credit or bad credit.

If you want to build credit, a secured credit card can help you climb the first rungs on the credit ladder. Once you put down a security deposit, you can use a secured card just like a regular credit card. The card issuer then reports your payment history to the credit bureaus, helping your credit score move in the right direction.

But where can you find secured credit cards in Canada, and what other alternatives are available? Keep reading to find out.

Secured credit cards in Canada and alternatives

ProviderHow much you can borrowInterest rateFeeRequired deposit
Neo Secured Mastercard$50 – $10,00019.99%–29.99% (up to 25.24% in Quebec)$119.88/yearMin. $50Go to site
Capital One Guaranteed Secured Mastercard$75 – $2,50029.9% (21.9% in Quebec)$0Min. $75
Home Trust Secured Visa$500 – $10,00019.99%$0Min. $500
Nyble credit line$30 – $2500%Optional $11.99/month for a premium membership for instant transfersN/AGo to site
KOHO cash advance$20 – $5000%From $2/monthN/A
Go to site
Bree early pay$20 – $7500%Optional $2.99 – $45.99 fee per instant transferN/AGo to site
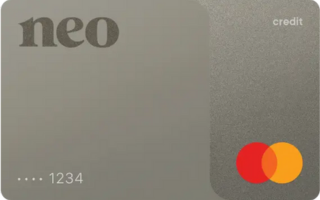
Neo Mastercard

1. Neo Secured Mastercard

How it works

Canadian fintech Neo Financial offers a variety of credit cards, and all of them are available with a secured credit limit. Options range from the entry-level Neo Mastercard through to premium cards like the Neo World Elite Mastercard. All you have to do is provide a security deposit to set your credit limit, then start spending and rebuilding your credit.

The Neo Secured Mastercard is the most common secured version.

Rates and fees

  • Neo Mastercard: 19.99%–29.99% (up to 25.24% in Quebec), $119.88/year
  • Neo World Mastercard: 19.99% - 29.99% (up to 25.24% in Quebec), $119.88/year
  • Neo World Elite Mastercard: 19.99% - 29.99% (up to 25.24% in Quebec), $149/year
  • United MileagePlus Neo World Elite Mastercard: 19.99% – 29.99%, $89/year
  • Cathay World Elite Mastercard: 19.99% – 26.99%, $180/year

Go to site

Rewards and perks

Check the table below for an example of the rewards you can earn each year with a Neo cash back Mastercard.

CategoryNeo MastercardNeo World Mastercard – Shop & DineNeo World Mastercard – Gas & GroceryNeo World Mastercard – EverywhereNeo World Elite Mastercard – Shop & DineNeo World Elite Mastercard – Gas & GroceryNeo World Elite Mastercard – Everywhere
Fee$119.88*$119.88*$119.88*$119.88*$149$149$149
Grocery cashback––2%1%–5%2%
Food & drink cashback–2%–1%3%–2%
Recurring payments cashback––2%1%–4%2%
Gas and EV charging cashback––2%1%–3%2%
Retail shopping cashback–2%–1%3%–2%
Everything else cashback–0.5%0.5%1%1%1%2%
Partner cashbackUp to 15%Up to 15%Up to 15%Up to 15%Up to 15%Up to 15%Up to 15%
Example total cashback per year$60$258$414$342$456$834$624
What you keep after fees-$59.88$138.12$294.12$222.12$307$685$475

*This is the Build fee. Build is Neo’s level two membership, with perks like a higher savings rate and credit monitoring.

Travel

If you prefer your rewards with a travel flavour, here’s how the Cathay World Elite Mastercard and the United MileagePlus Neo World Elite Mastercard compare.

United MileagePlus Neo World Elite MastercardCathay World Elite Mastercard
Annual fee$89$180
Earn rate
  • 1.25x miles per $1 spent on United Airlines and Star Alliance flights
  • 1x mile per $1 spent on dining and grocery purchases
  • 0.75x miles per $1 spent on everything else
  • 1x Asia Miles on purchases in Canada
  • 2x Asia Miles on purchases in foreign currencies
  • 4x Asia Miles on Cathay Pacific flights
  • 5x Asia Miles at Neo partners
Example: If you use the United MileagePlus Neo World Elite Mastercard and spend $3,000 on United Airlines flights, $12,000 on dining and groceries and $14,000 on everything else annually, you would earn 26,250 miles. That’s potentially enough to cover flights for a round trip from Toronto to a major US destination like New York.
Example: If you use the Cathay World Elite Mastercard and spend $30,000 in Canada per year, $7,500 internationally and $1,500 at Neo partners, you would earn 52,500 Asia Miles. That’s enough for an economy flight from Vancouver or Toronto to Hong Kong, and you’d still have plenty of miles left over to spend on short-haul flights in Asia.

Eligibility requirements

  • Age of majority in your province or territory
  • Security deposit of at least $50
  • Neo Mastercard: No minimum income requirement
  • Neo World Mastercard: Minimum $50,000 personal or $80,000 household income
  • Neo World Elite Mastercard: Minimum $80,000 personal or $150,000 household income
  • United MileagePlus Neo World Elite Mastercard: Minimum $80,000 personal or $150,000 household income
  • Cathay World Elite Mastercard: Minimum $80,000 personal or $150,000 household income

Neo Financial review

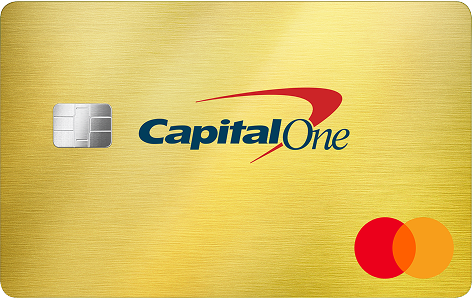
Capital One Mastercard

2. Capital One Guaranteed Secured Mastercard

How it works

This card is designed to help you build or repair credit. You can get pre-approved online without hurting your credit score, and once you’ve provided a deposit as collateral, you can start using your card just like you would a regular Mastercard. Your card use and payments are reported to the credit bureaus to help get your credit back on track.

Rates and fees

  • 29.9% (21.9% in Quebec) interest rate
  • $0 annual fee
  • $75 minimum security deposit

Rewards and perks

The bad news is you can’t earn cash back or rewards points with this card; the good news is that it does come with a range of insurance covers. Purchase assurance and extended warranty cover headline the list, while the Price Protection Service refunds the cost difference when an item you purchased then goes on sale. And if you’re planning your next vacay, travel accident and baggage delay insurance are also included.

Eligibility requirements

  • Age of majority in your province or territory
  • Authorized to access credit
  • No existing Capital One account or a pending application for one
  • Haven’t applied for a Capital One account more than once in the last 30 days
  • Haven’t had a Capital One account that was not in good standing in the last year
  • Aren’t in legal recoveries with Capital One

A cardholder’s insights into the Capital One Guaranteed Secured Mastercard

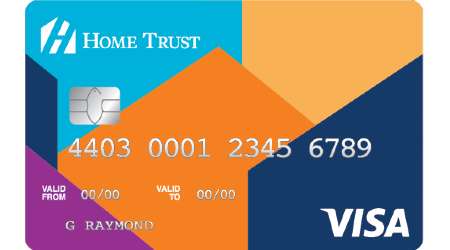
Home Trust Secured Visa

3. Home Trust Secured Visa

How it works

The Home Trust Secured Visa works exactly how a secured credit card should. You fork out a security deposit of at least $500, and that amount becomes your card’s credit limit. You can then pay with your card in store and online anywhere Visa is accepted, and Home Trust reports your card use to the credit bureaus to help boost your credit score.

Rates and fees

  • 19.99% with no annual fee; or
  • 14.9% interest rate with a $59 annual fee
  • Security deposit of $500 - $10,000 required

Rewards and perks

If you’re looking for cash back or other rewards, look elsewhere. This is a no-frills card that does exactly what a secured credit card is designed to do: help you build credit.

Eligibility requirements

  • Permanent Canadian resident (excluding Quebec)
  • Age of majority in your province or territory
  • Not currently in bankruptcy
  • Pay a minimum security deposit of $500 from a Canadian account in your name

Home Trust Secured Visa review

Don't forget about credit unions

Vancity

Vancity offers six secured enviro Visa credit cards. Choose from no-annual-fee, low-interest, rewards and travel cards, then provide a security deposit and start spending. Your deposit will earn interest. Available in BC only.

Collabria cards

Collabria credit cards are widely offered by credit unions across Canada, but do they have a secured version? It depends on the credit union. Visit your local credit union branch or phone them up to ask what options are available to you. They may be willing to offer you a secured credit card, particularly if you already have an ongoing banking relationship with them.

Nyble

4. Nyble credit line

How it works

An interest-free line of credit that can help you build credit might sound too good to be true, but that’s exactly what Nyble offers. You can apply in minutes online with no credit check; instant funding is available; and you won’t owe a cent of interest when you repay your loan.

Rates and fees

  • 0% interest
  • $11.99 monthly membership fee required if you want instant funding (otherwise it could take one to three business days to get the money)
  • No late fees

Go to site

Rewards and perks

There’s more to Nyble than just building credit. Not only can you check your credit score for free, but you also earn reward points for on-time payments. Upgrade to a premium membership to get 5x the rewards earn rate, plus other perks like instant payments, balance protection insurance and identity theft coverage.

Your points can be redeemed for gifts, including gift cards from popular retailers like Starbucks, Amazon and Tim Hortons.

Eligibility requirements

  • Age of majority in your province or territory
  • Active bank account
  • Meet minimum income requirements
  • Minimal NSF transactions on your account

Nyble review

KOHO logo

5. KOHO cash advance

How it works

If you’re a KOHO member, you can subscribe to KOHO Cover and get an interest-free cash advance of up to $500. No credit checks. No minimum income requirement. The money is available instantly, and you have the flexibility to repay at any time.

Rates and fees

  • 0% interest
  • Monthly fee from $2
  • KOHO Essential plan is available for free, but Extra costs $12/month and Everything costs $14.75/month
  • $0 NSF fees

Cash Advance Apps
ENDS SOON
Get $75 from Finder
Become a Finder member, then open and fund a new KOHO account through Finder as a first-time customer. Keep the account open until February 15, 2027. Offer ends December 30, 2026. Separate T&Cs apply.
SIGN UP & GET $75

Rewards and perks

Sign up for Cover and you’ll get access to free financial coaching valued at up to $425. And thanks to your KOHO plan, you’ll be rewarded with unlimited 1–2% cash back for your spending on groceries, transportation, and food and drinks. Add 2%–3.5% interest on your savings balance into the equation, and the deal sounds even sweeter.

But just how much value can you get? Let’s say you have an Essential plan and you spend $1,200 per month on cash back categories—that works out to $144 cash back per year. If you also use your KOHO account as a savings account, you can earn 2.5% interest on an initial deposit of $2,000 and extra deposits of $250 each month. This means your balance will increase to $5,085 by year-end (including $85 in interest).

Eligibility requirements

  • Canadian citizen or permanent resident
  • Age of majority in your province or territory
  • KOHO account holder

KOHO Cover

Bree

6. Bree early pay

How it works

Need some extra cash to pay an urgent bill? An interest-free cash advance of up to $750 from Bree could be just what the doctor ordered. There are no credit checks, mandatory charges or late fees to worry about, and instant funding is available for a fee.

Rates and fees

  • 0% interest
  • $0 late fees
  • $2.99 – $45.99 fee for instant funding (otherwise it could take one to three business days to get your funds)

Go to site

Rewards and perks

Sign up for a completely optional Bree membership to make the most of a budgeting tool you can use to track your income and expenses. Members also get a weekly newsletter with money management tips. It’s not the most exciting of perks, but it could be useful.

Eligibility requirements

  • Age of majority in your province
  • Canadian resident
  • Active chequing account
  • Recurring income and receive your paycheques as direct deposits
  • Minimum of two consecutive paycheques deposited into your account
  • Enough funds after your next paycheque to repay your advance

Bree review

What are the best secured credit cards in Canada?

Before you can decide which secured credit card is the best fit, you need to work out what your top priority is.

If your main focus is accessing credit that’s easy to qualify for, a cash advance app might actually be a better choice than a secured credit card. These apps don’t check credit, and they don’t require you to shell out a security deposit. They also accept a variety of income types.

If your top priority is building credit, consider secured credit cards and the Nyble cash advance app. Nyble reports to the credit bureaus to help improve your credit score, but it only offers small credit amounts of up to $250.

Among the credit cards, the Home Trust Secured Visa is worth checking out if you want the lowest interest rate (14.9% – 19.99%). But it requires a minimum security deposit of $500, so you might want a card with a lower minimum like the Capital One Secured Mastercard ($75).

A Neo secured card offers the best perks, but fees will apply.

Does it ever make sense to get a secured card if you have good credit?

Regular, unsecured credit cards offer better rewards and don’t require you to tie up a big chunk of cash as collateral. So if you have good credit, why would you consider a secured credit card?

A secured card doesn’t make sense most of the time, but there are some exceptions:

  • Controlling spending. Your deposit on your credit card is your credit limit, which can be useful if you need extra motivation to stick to a tight budget. You can also use your card for specific expenses only, such as a vacation, keeping it separate from your day-to-day spending.
  • You still don’t qualify for a regular credit card. Factors other than your credit score can stop you from qualifying for an unsecured card. Maybe you’re a newcomer to Canada, your income is inconsistent, or you only have limited credit history. In those cases, a secured card might make sense.
  • Fraud protection. If you’re worried about falling victim to fraud or theft, carrying a secured card with a low credit limit will limit your losses if something goes wrong.

Do any of these banks have secured credit cards?

RBC

Does RBC offer a secured credit card? Unfortunately not.

Newcomers to Canada can check out RBC’s Newcomer Advantage program for help getting a credit card, while the bank also offers a range of student credit cards to help you start building credit history.

TD

No, you can’t get a TD secured credit card in Canada.

But TD does offer a secured card in the US—the TD Cash Secured Credit Card—so don’t be fooled if you see this pop up in your search results.

Scotiabank

No, you can’t get a Scotiabank secured credit card.

But newcomers can check out the StartRight program, while students can check out the bank’s range of student credit cards.

CIBC

You can’t get a CIBC secured credit card.

But there are five CIBC student credit cards to choose from. The bank also offers credit cards for newcomers, with no security deposit or credit history required.

BMO

You can’t get a BMO secured credit card in Canada. But US residents can check out the BMO Boost Secured Credit Card, so don’t be confused if you see it listed in your search results.

If you’re a new arrival to Canada, the BMO NewStart Program includes ways to access credit even if you don’t have a credit history. BMO also has newcomer and student credit cards, plus a BMO Prepaid Mastercard you could check out.

National Bank

No. Just like the other big banks, National Bank doesn’t have secured credit cards.

However, its Newcomer Program may allow you to get a credit card with no prior Canadian credit history.

How do I pick the best secured card for me?

Look at these key factors when choosing a secured credit card:

  • Eligibility requirements. Before you go any further, run your eye over the terms and conditions to check whether you qualify for the card. Eligibility criteria are typically pretty lenient, but there may be an unexpected requirement that rules you out.
  • Interest rate. Check the interest rate that applies to purchases and cash advances. This is especially important if you don’t pay your balance off in full each month.
  • Annual fee. Basic cards tend to have no annual fee, but rewards cards often come with annual charges. Some cards also give you the option to choose either no annual fee and a higher rate, or pay an annual fee and get a lower interest rate.
  • Other fees. Check the fine print for details of any other fees you may be hit with, such as foreign transaction fees, cash advance fees or one-off fees to get additional cards.
  • Credit limit. Check the minimum security deposit as well as the maximum credit limit for the card. Do they suit your needs?
  • Credit building. Make sure the card issuer or cash advance app will report your on-time payments to the major credit bureaus. The purpose of a secured card is to build credit so you can someday graduate to an unsecured card, so it’s vital that your card issuer holds up their end of the bargain.
  • Cashback or rewards. Many secured credit cards don’t let you earn cash back or rewards on your spending, but some do. Compare cash back or air miles earn rates, calculate whether you will earn enough rewards to justify the card’s annual fee, and watch out for cash back spending limits. And don’t forget to look for any bonus point welcome offers available to help sweeten the deal.
  • Insurance. From extended warranty and purchase protection to a variety of travel insurance covers, check what insurance protection is included for added peace of mind.

Bottom line

A secured credit card is an important stepping stone on your journey back to good credit. There are several options to choose from too, so the best secured credit card for you depends on what you want in a card—a low interest rate, no annual fee or cash back rewards. Compare a range of options along with cash advance app alternatives before deciding where to apply.

Frequently asked questions

Leanne Escobal's headshot
To make sure you get accurate and helpful information, this guide has been edited by Leanne Escobal as part of our fact-checking process.
Tim Falk's headshot

Tim Falk is a freelance writer for Finder. Over the course of his 20-year writing career, he has reported on a wide range of personal finance topics. Whether you're investing in stocks and ETFs, comparing savings accounts or choosing a credit card, Tim wants to make it easier for you to understand. When he’s not staring at his computer, you can usually find him exploring the great outdoors. See full bio

Tim's expertise
Tim has written 595 Finder guides across topics including:
  • Banking
  • Personal Loans
  • Car Loans
  • Stock Trading
  • Cryptocurrency
Go to site