BMO Performance Chequing Account
- Earn up to $1,100
- Exclusive: Get an extra $175 reward from Finder + a $75 BMO referral boost
- Get up to 5.00% promo interest with a linked savings account
Us Canadians have a lot of banking options to choose from—options like brick-and-mortar banks, digital-only banks, credit unions and fintechs, all vie for your business. So when it comes time to choose the best debit card, how do you know which is the best option for you?
That’s where we come in. Our team at Finder Canada analyzed over 1,000 data points for debit and prepaid debit cards from financial institutions across the country to determine this list of the best debit cards in Canada. We looked at features like debit fees, ATM access, travel perks, spending rewards and more.
Keep reading to choose the best debit card in Canada for you and learn tips for how to use your card for online shopping, avoid fraud and more.
| Debit card | Online purchases | Cobranding | Native ATM network | Standout features |
|---|---|---|---|---|
| BMO debit card | ✓ | Mastercard | All BMO ATMs |
|
| EQ Bank Card | ✓ | Mastercard | Any ATM in Canada |
|
| Scotiabank debit card | ✓ | Visa | Global ABM Alliance |
|
| Tangerine Visa Debit card | ✓ | Visa | Global ABM Alliance |
|
| Wealthsimple prepaid Visa Platinum card | ✓ | Visa | Any ATM in Canada |
|
| PC Money Account debit card | ✓ | Mastercard | PC Financial ATMs |
|
| Scotiabank student debit card | ✓ | Visa | Global ABM Alliance |
|
To determine this list of best cards, Finder Canada analyzed 70+ debit and prepaid cards across 22 financial institutions. We compared cards from traditional banks, digital banks and credit unions, and we narrowed down the list to the top 7 cards.
We ranked debit and prepaid cards based on 16 data points within four major categories. Here's how we ranked and weighted each product:
No single debit or prepaid card will be the best choice for everyone, so thoroughly compare your options before picking your new card.
Debit cards (also called client cards or bank cards) are payment cards issued by your bank to give you access to your chequing or savings accounts. You can use debit cards for in-store purchases and ATM withdrawals in Canada or internationally. If you have a Visa Debit card or Debit Mastercard card, you can also use your card to make purchases online.
Debit cards only allow you access to your account balance, unless you have overdraft protection, which lets you dip into a negative balance (usually for a fee). If you want access to money that is not in your account, consider a credit card instead.
The best debit card in Canada to have is the BMO debit card linked to the BMO Performance Chequing Account because it comes with unlimited transactions, a generous welcome bonus and other perks like fee rebates on select credit cards.
But if you’re looking for the best travel debit card, we recommend the EQ Bank Card—a prepaid debit card with no FX fees, no domestic or international ATM withdrawal fees, cashback rewards on your spending and earned interest on your card balance.
Visa Debit cards and Debit Mastercards work like any other debit card, giving you access to the money from your chequing account. The advantage of Visa Debit and Debit Mastercard cards is that, unlike traditional debit cards, they allow you to make online and phone purchases like you can with credit cards.
They don’t give you access to credit, but they do come with a card number, expiry date and CVV number. The best debit cards in Canada, including many of the cards listed here, will come with this functionality.
Functionally, both Visa Debit and Debit Mastercard cards are equally good as both types of cards allow you to use your debit card for online purchases, which is the primary function of debit cards being cobranded with either company.
That said, Visa has a slightly bigger overall market share than Mastercard (at least it does in Europe, according to a Global Payments Report 2025), making it pull slightly ahead as a better option for many when it comes to debit cards, prepaid cards and credit cards.
Yes, most debit cards in Canada have a Card Verification Value (CVV) code, which can also be known as a card verification code (CVC). This number acts as an additional security step in fraud prevention by proving to merchants that you have the actual debit card with you when making online or phone purchases. Only Visa or Mastercard cobranded debit cards will have CVV numbers.
The three-digit CVV security code can be found on the back of your debit card, either right beside or below the signature box beneath the long black magnetic strip. Don’t get it confused with the 16-digit card number or the four-digit expiration date.
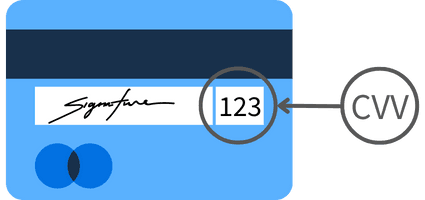
If your debit card does not have a CVV security code, it’s likely because it is a traditional debit card – not a Visa Debit or Debit Mastercard – and cannot be used for online or over-the-phone purchases.
If you would like switch your card for one that you can use beyond in-store purchases, contact your bank to see about upgrading your card, or consider opening a new account that comes standard with a Debit Mastercard or Visa Debit card from the accounts listed here.
Yes, you can use your debit card in the US just like you would use it in Canada as long as it has a magnetic stripe and PIN number. The main factor to keep in mind when using your Canadian debit card in the US is that you’ll be charged an exchange rate markup and foreign transaction fee of around 2% to 3% of the transaction value.
If you want to save money when using a Canadian debit card in the USA, consider opting for a debit card with no foreign transaction fees.
You can compare the best debit cards in Canada, and the bank accounts they’re attached to, by looking at the following features:
The best type of debit card will be from a well-established bank, allow you to make unlimited transactions, give you access to a large ATM network so you can withdraw cash when you need it and be compatible with your phone’s digital wallet.
That’s why BMO topped our list of the best debit cards in Canada, but there other factors—like rewards, cashback and travel perks—you can consider too.
The best debit cards in Canada come with a number of benefits, although there may be some drawbacks.
To get a debit card, you’ll need to open a bank account with a Canadian bank, credit union or fintech. Follow these steps to open an account and get a debit card:
Many banks allow youth to open a kids chequing account – and get a debit card – between the ages of 12 to 16 years old without a parent or guardian with the required ID. If a parent or guardian can get involved, any child under 18 years old can open a bank account at the major banks in Canada, and in most cases, get a debit card linked to that account.
If you’re looking for a debit card for your child, compare debit cards for kids.
Using your debit card is simple. Just swipe or insert your card into the debit terminal, select the account you want to debit the money from, enter your 4- or 6-digit PIN number and press OK.
If your car is equipped with Tap & Go or payWave, just hold your card near the terminal to pay – no PIN required.
Debit transactions in Canada are processed through a payment processor system like Moneris. Your merchant will also pay a fee for debit transactions. The amount of your purchase is deducted from the chequing or savings account associated with your card, whichever you selected
Tap payments are a type of contactless payments that work via NFC (Near Field Communication), where you simply need to hold your car close to the debit terminal to pay with your debit card. You can’t debit from your savings using tap. Instead, money is automatically debited from your primary chequing account.
Tap & Go and payWave are both technology that allows you to securely pay for your purchases without having to swipe your debit card or enter your PIN. Instead, you simply tap or wave your debit card at the point of sale.
Take a look at your debit card and see if it has the payWave or Tap & Go symbol on the front. The symbol consists of four curved lines and will likely be located on the right-hand side of the card, but this can differ between cards. If your card doesn’t have the symbol, call your bank to see if you can get a new card.
 You can add most debit cards in Canada (including any of the ones on our list of the best cards above) to your phone’s digital wallet so you can pay with your debit card using Samsung Pay, Google Pay or Apply Pay.
Your phone uses NFC, so you simply need to select your debit card from your digital wallet and hold your phone near the debit terminal to make a payment.
In order to make purchases with your debit card using your smartphone’s digital wallet, you’ll need to first add your debit card to the digital wallet by following these steps:
You can now use your debit card directly from your phone by tapping your phone at any terminal that accepts tap payments.
Here are some common questions and concerns about how debit cards work in Canada and what you might need to consider when choosing the best option for you.
 Debit card fraud: is your money at risk?
Like any financial product, even the best debit cards in Canada come with the risk of being exploited by scammers. But there are steps you can take to protect your money from potential threats.
Debit card fraud occurs when someone else obtains your debit card details and makes transactions on your card without you knowing. If you report a fraudulent transaction on your card, your bank should deactivate your card immediately in order to prevent the person from making more transactions. An investigation will likely take place to help retrieve or replace your money.
You should always check your debit card statement to make sure all of the transactions listed are legitimate. This will help you identify any unusual activity.
If your card is lost or stolen, let your bank know straight away, even if you’re travelling overseas. In most cases, your bank will immediately cancel your card and will send you a replacement card as soon as possible.
This depends on your bank and the situation. Many of the bigger banks offer a 100% money-back guarantee on fraudulent transactions if you comply with the card’s conditions of use. For more information, speak to your financial institution.
There are a number of ways that debit cards differ from credit cards. The most important difference relates to how you access funds. Debit cards only let you access cash that you’ve got saved up in your account. Credit cards let you “borrow” money that you eventually have to pay back with interest.
Other differences between debit and credit cards include:
While most Canadians have a debit card, many prefer to make purchases using a credit card. This is because credit cards tend to offer more rewards and benefits than debit cards.
If you’re looking for a debit card that comes with lower fees, you’re not alone. It turns out that the majority of Canadians are also most concerned about banking fees when choosing their next bank account, according to our Finder: Consumer Sentiment Survey March 2026.
It turns out the that, when asked to choose their top three most important features, 63.72% of Canadians said they’re looking for an account with no or low monthly fees, 50.42% are looking for no or low transaction fees and 44.18% said they want free e-transfers.
That’s why all of the debit card we chose as the best in Canada come with free transactions and e-transfers, while most don’t charge a monthly fee. You can also check out our guide to the best no-fee chequing accounts in Canada to learn more.
The Finder: Consumer Sentiment Survey January 2025 showed the same top and bottom results (with slightly different vote counts). Fee-centred features ranked the highest, while budgeting and expense-tracking tools and mobile wallet accessibility ranked the lowest.
The best debit cards in Canada offer perks like unlimited monthly transactions, access to a vast ATM network and sometimes even rewards on your spending. Once you picked the right debit card for you, you can start using your card to make purchases in store, online (if is a Visa Debit or Debit Mastercard) and manage your finances through it’s mobile banking app. Just make sure you’re staying within any transaction limits so you don’t get charged extra fees.
BMO Performance Chequing Account

Explore key banking statistics and figures from the Finder: Consumer Sentiment Survey January 2025.

Compare the features of 8 of the best no-fee chequing accounts in Canada, and find out how to avoid transaction fees.

Earn cash, rewards points, bonus interest rates and more with these new bank account offers and promotions.

Learn about the different types of bank accounts for your teenager and how to choose the right one.

Compare chequing accounts and learn about our top picks. Compare different features and see which one is right for you.

Compare and open a bank account online in Canada in as little as 5 minutes. Learn what you need to apply and how to get started today.
Your guide to the best virtual debit cards in Canada, how they work, and their pros and cons.
Get competitive exchange rates and pay no foreign transaction fees when you spend money internationally with this fee-free debit card.
Use this versatile Scotiabank Debit Card to earn points and make purchases online.
Apply for a debit card with this Big Five bank to make purchases online or in-store directly from your bank account.
It’s a straightforward and convenient process to use your debit card online, but paying with a credit card may be safer.
If you’ve fallen victim to debit card fraud, you may be eligible to receive a refund. Learn more in our comprehensive guide to debit card fraud.
Take preventive measures to avoid having to worry about your debit card being declined.
Make sure you have one of these debit cards before you travel overseas.
Linking your debit and credit card to your PayPal account can save you time when shopping online. Here’s how.
Convenience fees can apply to debit card transactions as well as credit card payments, but only a small number of select merchants can legally charge them in Canada.
