Access a Large Network
- Accepts bad credit borrowers
- Easy online application
- Quotes from multiple lenders
- Access cash within 1-3 business days
They’re economical, environmentally friendly, energy efficient, and they encourage you to stick to a minimalist lifestyle – it’s no wonder you may be considering joining the tiny house movement.
Financing is likely on your cards to help bring your dream home to life. Here’s a comprehensive list of the various options you have on the table to help you finance your tiny home.
If you’re buying a standard sized home, a mortgage is the traditional route you’d take to help you with your milestone purchase. Tiny homes, on the other hand, don’t work in the same way, usually because tiny homes cost far less than their full-sized counterparts.
With this difference in mind, here are the most conventional options you have to help you build or buy your tiny house:
If you’re looking to buy a tiny house with a solid foundation or want to build your own RV, you might want to consider taking out an unsecured personal loan. A personal loan is provided as a lump sum which you’ll repay over the course of a few years. You can typically use these term loans for any legitimate purpose and don’t have to put your home up as collateral.
Access a Large Network
Get Multiple Offers
Fast Financing
Many tiny houses are on wheels. If that’s what you’re looking for, RV loans could help you with funding. Just like securing financing for a regular-sized vehicle, RV loans provide you with the funds to help you purchase a new or used recreational vehicle, including motor homes, travel trailers, toy haulers and campers.
If you’re building your home, you might want to consider taking out a line of credit. It works almost like a credit card, giving you a specified credit limit to use how you like. While personal loans give you a lump sum of funding you need to repay within a fixed amount of time, a line of credit stays open as long as you keep up with payments. Once you repay what’s withdrawn, you can re-access the money. Access to a line of credit can prepare you for unexpected expenses that don’t factor into your initial calculations.
While your tiny home likely won’t be eligible for a traditional mortgage, you may still be able to qualify for a chattel mortgage. A chattel mortgage is a mortgage for movable personal property, unlike a regular home. These work more like car loans than mortgages; your lender will technically own your home until you finish paying off the loan.
They tend to have lower interest rates than personal loans and may have less strict eligibility criteria than other financing options.
When homebuyers purchase a traditional house, they often seek out financing through a lender that’s partnered with the homebuilder. In this same way, tiny house buyers can link up with a lender affiliated with the builder constructing their new property. Your builder may even recommend this option for financing your construction and offer incentives to take up their offer.
If you already own a home and want to build or buy a second tiny house, you can leverage the equity you’ve built up in your first home to finance your next property purchase. Keep in mind, you’re using your home equity as collateral.
While home equity loans provide borrowers with a single lump sum of cash that’s repaid with set terms, a home equity line of credit (HELOC) allows homeowners access to funds as needed, just like a regular line of credit. Once again, you’re using your home equity to qualify for this account.
Not necessarily. You may need an unconventional form of financing for your unconventional home. For starters, it may be difficult to find mortgage lenders that market tiny house mortgages because they’re so niche. Most mortgages tend to come with minimum limits on how much you can borrow, with tiny houses being on the lower end of the price range. Other lenders may explicitly state that their home loans apply only to properties fixed on a solid foundation, which may exclude tiny houses that are designed to be portable.
With these limitations at hand, your best bet is to consider chattel mortgages, RV loans and personal loan products to finance your tiny house. It’s worth checking with your current lender though, to see if your tiny home fits the building code requirements to qualify as a conventional property
With tiny homes still being a novelty in Canada, make sure you do some comparison shopping with your financing options and take stock of what you need from your tiny house loan. Here are the key determining factors to consider:
With any milestone purchase, consumers need to consider the risks involved, and tiny homes are no exception. While they may come with lower operating costs and less upkeep, there are some financial red flags to be wary of too.
Imagine this scenario: Amelia recently graduated from university and was loaded with student debt. Owning a home was always a dream of hers, but getting there seemed impossible with her monthly student loan payments and entry-level job. A tiny house, however seemed like a possibility — which became a reality when she found a pre-built RV house for $68,000 through a tiny house manufacturer.
Here’s how the costs broke down:
She looked around for different personal loans and decided to finance directly through the manufacturer — it was easier and the rates weren’t that different from what other lenders were offering. She got a 15-year loan with a 5.59% interest rate and a 20% down payment of $13,535.60 — which her parents loaned her without interest. This meant that she had 15 years of monthly repayments of $445.
Other costs included a $97.02 annual registration fee for a 9,000-pound trailer and a $950 monthly rental fee for an RV spot with electricity and water included.
Her total housing costs added up to about $1403.08 per month.
 What is a tiny house?
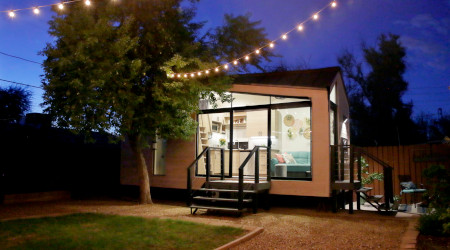
A tiny house is a residential building that is no more than 400 to 600 square feet in size. Think of RVs converted into miniature, portable homes or tiny cabins, containers or loft-style properties in which every inch is put to use strategically. These tiny homes can range from bare bones Spartan, to rustic to futuristic, and even completely green-friendly with solar panels, a rainwater catch, filtration system and a composting toilet so you can live off of the grid.
Tiny houses are most often defined as residential buildings less than 500 square feet — though sometimes anything less than 1,000 square feet is considered a tiny house. They tend to cost a fraction of a regular home, which can come with thousands of square footage. But that doesn’t mean it’s cheap. How much you can expect to pay depends on whether you plan on buying a tiny house or building one.
It also depends on your area’s regulations. Some local governments require homes with a foundation to be a certain square footage. Others have restrictions to camping on private land — which applies to your home if it’s classified as an RV. Make sure you know your local laws before deciding where or what to build.
This can be the easiest way to do things, but there are still several costs to consider, especially if it’s an RV. If your home is built on solid foundations, your main costs are the home itself and the land.
If you’re buying an RV, you can either buy land, park it on private property belonging to friends or family, rent a long-term RV spot or move it around public land. But you’ll also pay for a trailer license, yearly RV registration fees — not to mention having a car strong enough to drive it around.
| Expense | Typical cost |
|---|---|
| Tiny house or RV, including extras and shipping fees | $70,000–$500,000 |
| Buying land | Over $200,000 (plus property taxes), depending on location |
| Renting an RV spot | $500 per month plus water and electricity hookup fees (around $450 per month) |
| RV registration fee | $20–$200 a year, depending on regulations |
Building a tiny house, is usually cheaper than buying one, with costs typically adding up to between $10,000 to $40,000. But they can take a long time to build — sometimes even years. On top of the expenses like buying land and getting a trailer license listed above, here are some of the main expenses you can expect to come across when building your new home:
| Expense | Price range |
|---|---|
| Trailer | $10,000–$35,000 |
| Doors and windows | $1,000–$3,000 |
| Lumber | $3,000–$10,000 |
| Insulation | $500–$2,000 |
| Roofing | $500–$1,000 |
| Siding | $1,500–$3,000 |
| Wall paneling | $500–$2,000 |
| Flooring | $300–$2,000 |
| Light fixtures | $200–$800 |
| Hiring an electrician | $1,500–$3,000 |
| Water heater | $500–$1,000 |
| Shower tile | $300–$1,000 |
| Toilet | $800–$1,500 |
| Other bathroom fixtures and plumbing | $600–$2,000 |
| Space heater | $200–$800 |
| Cabinets (storage and kitchen) | $1,500–$5,000 |
| Kitchen counter | $300–$2,000 |
| Kitchen appliances | $1,000–$3,000 |
| Screws, nails etc. | $500 |
| Paint | $50–$200 |
| Your time | 400–600 work hours |
Don’t have the time — or skills — to do all that work? Some manufacturers can meet halfway with a tiny house shell. All the basics are pre-installed like water lines, electricity and sewage systems, but you can still customize it to your liking. These typically cost between $10,000 and $35,000.
Or you can buy a prefab tiny house kit, which you can put together yourself for less than $10,000 or hire someone to do the work for you.
Tiny houses may be trendy now, but they might not be worth it if…
Tiny house living is a lifestyle that’s not for everyone. While it’s cheaper than buying a house, you probably won’t be able to sell it for a profit like other types of real estate. Make sure everyone’s onboard before you buy one and also be aware that life changes — like an unexpected pregnancy — have made many families reevaluate their decision.
If you’re sure it’s the right thing for you, you might want to start by comparing personal loans to get an idea of how much it’s going to cost you on a monthly basis and in the long run.
Check out these options if you’re looking for loans like Lamina.
How to access flexible financing with a line of credit in Canada even if you have bad credit.
Here’s the key info you need to know to get the right $40,000 loan for your needs.
You can get a cash advance, payday loan or personal loan with a low income, but watch out for high interest rates.
Find out where you can take out a $6,000 loan in Canada and what you need to qualify.
You can take out an installment loan, cash advance or payday loan in Alberta using your child tax benefit.
Want to find the best rates for your next personal loan? Compare lenders with Loans Canada, a well-known online loan search platform.
Want to find the best deal on your next personal loan? Compare lenders with this innovative online platform.
Compare rates and terms of quick $10,000 personal loans in Canada.
Find out if you’re eligible for a $3,000 or even $3,500 loan, and learn how to compare your loan options in Canada.
